Small business lending software for community banks, credit unions, non-bank lenders, and fintechs. Term
loans, working capital, invoice and equipment finance, on one platform.
Segment your SME portfolio by repayment behavior, identify accounts worth pursuing, and recover more without straining relationship value.
25%
improved recoveries
Workflow automation lowers the cost per loan on smaller tickets and keeps the cost to serve
an SME book viable at scale.
60%
cost reduction
Small business lending software
for the complete lending journey
Fast onboarding
Give small business owners a digital experience that works on any device. Capture business
financials and all supporting documents quickly through automated data prefill and open banking
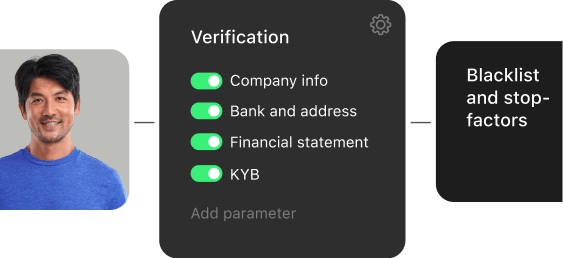
integrations. KYC/KYB verification, affordability checks, and smart document collection designed
for high-volume SME intake are included in the flow.
Learn more
Intelligent origination
Approve more SME borrowers through rule-based credit decisioning, AI-powered scoring, plus
real-time access to accounting, banking, and bureau data. Configure loan products with
sector-specific eligibility criteria, tiered pricing logic, and risk conditions that reflect the
diversity of your SME customer base.
Learn more
Efficient servicing
Manage repayment schedules, limit reviews, and borrower communications across a large SME
portfolio from a single platform. Automate routine account management tasks, track payment
behaviour in real time, and raise early warning signals on accounts.
Learn more
Targeted collection
Segment delinquent SME accounts by risk profile and recovery potential. Deploy AI-driven
outreach and follow-ups and tailored repayment arrangements to maximize recovery rates while
preserving the borrower relationships that drive repeat business.
Learn more
Get your lending
product estimate
in 3 minutes
STEP:
/
Online onboarding
SME lending software that turns inquiries into funded loans
Most small business owners give up on a clunky application before they finish it. Offer a quick,
fully online journey to apply, backed by automated capture, prefill, and verification, so a higher
share of applications reaches a decision.
An applicant connects bank and accounting data through open banking, and the
platform prefills company financials, profitability ratios, and business plan
figures automatically. Owners finish in minutes instead of digging through
paperwork, so fewer drop off before submitting.
Cut approval times without cutting checks
Applicants submit company details, upload supporting documents, and sign agreements
without visiting a branch. HES LoanBox verifies ownership, runs affordability and
credit checks, and routes complete files to a decision, turning multi-day approvals
into same-session answers.
Keep SME borrowers engaged after drawdown
A white-label borrower portal lets business owners check balances, see repayment
schedules, upload documents, and pay on their own. Automated email and SMS reminders
reduce the chance of a missed instalment and keep owners involved from drawdown to
final repayment.
Grow through broker and introducer channels
Give brokers, accountants, and introducers workspace to lodge SME applications and
follow approvals for clients. Grow origination across partner channels without extra
headcount or new branches, and keep every submission visible in a single pipeline.
Smart task management for SME lending teams
Keep each SME file moving through your loan software for small business lending, with no stalls
between teams. Send each file to the right underwriter or analyst automatically and give all stages
one shared view of what needs action next.
Small business loan origination software for fast, well-documented
decisions
Slow manual reviews push small businesses to a faster lender, while thin data inflates defaults.
Automated verification and configurable underwriting turn every SME application into a quick,
well-documented credit decision your committee can stand behind.
Verify the business and its owners up front: KYB, AML, sanctions, and director
checks clear in moments. Pull business bureau records, open banking feeds, and
ownership data into one place, so every SME file reaches underwriting complete and
backed by audit-ready records.
Choose the decision path that fits each deal
Pick the decision path that fits each deal: automatic approvals on business rules
and custom scorecards for smaller tickets, semi-automated or full credit committee
review for larger, complex ones. The same engine reads EBITDA and key financials and
adapts to each loan size and risk.
Decide on live data, not stale statements
Open banking gives instant, permissioned access to a borrower live financial data.
Decisions draw on real-time cash flow, accounting feeds, and bureau records instead
of stale statements, so approvals are faster and built on what the business looks
like today.
Self-learning scoring by GiniMachine
GiniMachine estimates the probability of repayment for each applicant in your SME
book from how earlier loans performed, and the model is retrained on new outcomes,
so accuracy climbs while bad debt and manual checks fall.
Paperless from application to signature
Drop paper at every step of the SME loan journey. Intelligent OCR captures and
validates financial statements, IDs, and bank documents within moments, and embedded
e-signature closes the agreement remotely and shortens time to funding.
and much more
Automated contract generation
Generate binding SME loan agreements automatically from reusable templates with merge
fields. Errors in drafting disappear, drawdown moves faster, and every document stays within
the lending rules of each market you serve.
Multichannel borrower communication
Reach SME owners over text, email, and in-product alerts, fired automatically by rules
linked to payment behaviour and loan status. Borrowers stay informed at each stage while
your support team sheds repetitive work.
Unlimited SME product configuration
Build portfolio monitoring dashboards around the SME metrics your credit team tracks. Define
pricing, charges, schedules, and qualifying rules per product, sector, or campaign without
writing code.
Smart notification templates
Create message templates across text, email, and push with variable fields, then trigger
them automatically at each touchpoint, from application updates and approvals to payment
nudges and renewal prompts to repeat borrowers.
Role-based security and access control
Lock down sensitive company and director records with fine-grained access roles, password
rules you set, two-step sign-in, and per-device controls. Each action is captured in an
activity log, so access records stay audit-ready.
No-code workflow builder
Shape and revise SME lending processes in a point-and-click builder, no engineering
required. Lay out application paths, configure approval logic, branch decisions on
conditions, and ship a new workflow within days instead of quarters.
Configurable SME lending workflows
Loan servicing
Complete SME loan management software
HES LoanBox works as small business loan servicing software for the whole SME book, with live
balances and terms you can change mid-loan.
Run every SME loan from drawdown to payoff by your own rules. Accruals, fees,
restructuring, refinancing, and early repayments all process automatically, with no
spreadsheets and no month-end reconciliation scramble.
Manage the entire SME book
Handle term loans, working capital lines, top-ups, and consolidations from one
workspace. Adjust schedules, grant payment holidays, restructure balances, and post
partial payments on the spot, while every change is preserved in a complete history.
Collateral and security under control
Track and manage collateral across the whole SME book from one place. Register
assets against facilities, tailor security terms per deal, revalue on schedule, and
keep your position protected from drawdown through to final repayment.
Payment operations you can trust
Send disbursements and take repayments across pre-integrated gateways, ACH, SEPA,
card networks, and local rails. Balances refresh the moment money moves,
reconciliation runs on its own, and every transaction is logged in a full audit
trail.
Maximize commercial loan portfolio
performance with AI risk intelligence
Scoring made clear
Apply predictive scoring across the full credit lifecycle, from origination screening to
covenant monitoring and loss forecasting, with explainable and examiner-ready outputs.
AI-driven risk precision
Support commercial credit decisions with integrated AI scoring. Validate model performance
against your own portfolio and baseline; accuracy improvements are not guaranteed.
Smarter risk control
Set custom risk thresholds, surface deterioration before covenants break, and rebalance
pricing or limits to protect your commercial loan portfolio.
Loan collections
Automate SME loan collections
and recover more
Manual recovery is slow, costly, and quick to sour a client you want back. Hand outreach,
prioritization, and penalties to AI that predicts who will repay, chooses the best channel, and
respects the limits on every SME account.
Collectors handle fewer routine tasks, and overdue SME accounts advance through
recovery on schedule instead of waiting in a queue.
Tailor every recovery action with AI
Blanket dunning gives way to AI-driven collection strategies that adapt to how each
SME borrower pays and responds.
Prevent missed payments before they happen
Keep owners current with proactive personalized reminders via text, push, email, and
voice bot.
Manage penalties within set limits
Once a payment is missed, late fees and penalty interest accrue automatically, so
collectors spend no time calculating charges by hand.
Reporting and analytics for SME lending
Spin up dashboards around the SME metrics that matter to your team. HES LoanBox lets you export raw
data, define your own KPIs, and cut the book by sector, product, or region on demand.
100+ integrations behind your SME lending system
Open APIs and configurable connectors let HES LoanBox work as SME lending software inside your
existing stack, linking onboarding and scoring with payments, messaging, reporting, and core
banking.
What our SME lending software delivers
Unlimited customization
Customize without limits: rework modules, layer on features, tune the interface, and wire in
any service you use, from payment providers through to business bureaus.
One license, no seat fees
Pricing stays straightforward: a single license fee, with extra cost only for custom work.
Internal users and SME borrowers are uncapped.
Seasoned lending engineers
Work with a team that has spent 14+ years building lending software for SME and commercial
lenders across the US, Europe, and beyond.
3-month product launch
Your small business loan software can go live from 3 months on a standard scope, so lending
starts sooner and ROI arrives earlier.
Proven security
ISO 27001 certified, with SOC 2 controls. Runs on AWS or Google Cloud on a secure Java LTS
stack, with regular updates.
Hands-on support
Lean on a dedicated team for fast, expert help whenever your SME lending operation needs it.
Success stories
HES FinTech has been our reliable technology partner since 2012. I believe much of our success is due to the well-architected HES LoanBox solution.
An ISO 27001 and SOC 2 aligned ISMS holds security steady across operations,
with data encryption throughout, role-scoped access, and infrastructure
hardening at the host level. Internal and external audits confirm the
controls keep working.
HES LoanBox runs on-premises or in the cloud of any provider you choose.
Powerful backend tools
HES FinTech builds on free, open-source foundations such as Java LTS, BPMN
2.0, Camunda, and the Form.io modeler. That keeps you clear of extra
licensing fees beyond the platform source code.
The 2026 reality of
SME lending
46%
of applicants receive the full financing they request
Most applications are not fully funded. Fast data-driven underwriting lets lenders approve
more sound small businesses and thus close the financing gap. (Federal Reserve, 2025 Small Business Credit Survey)
29%
of applicants now turn to online and fintech lenders
Small businesses increasingly skip the branch for digital lenders. A fully online SME
platform is now table stakes for winning applications a bank once captured by default. (Federal Reserve, 2025 Small Business Credit Survey)
$5+
the true cost of every $1 lost to fraud
Each dollar of fraud carries far more than its face value once operations, recovery, and
lost trust are counted. KYB, AML, and AI checks at intake keep that cost off your book. (LexisNexis True Cost of Fraud, 2025)
44%
of lenders still fight fraud mostly by hand
Nearly half of institutions still chase fraud manually, which is slow and leaky. Automated
verification and AI scoring catch more at the door without slowing good borrowers. (LexisNexis True Cost of Fraud, 2025)
Start lending in just 3 months
You grow the book. The build stays with HES FinTech.
Think of SME lending software, also called SMB lending software, as the operating system for
a small business loan. One platform carries the borrower from the application stage all the
way to final payoff, and ideally back for the next facility. The strongest small business
lending software handle four things together: online onboarding with KYB plus document
capture, underwriting on company financials and cash flow, day-to-day servicing of term
loans and working capital lines, and recovery when repayments slip. HES LoanBox sits in this
category, aimed at lenders with real SME volume who would rather not bolt five separate
tools together.
What is the difference between SME lending software and a loan origination system (LOS)?
The two labels are often used interchangeably. Put simply, a loan origination system runs
application, approval, and funding. The broader SME lending category involves later stages,
such as repayments and drawdowns, limit and collateral reviews, restructures, and book-level
analytics. If you need to manage each loan from origination to recovery in a single
configurable system, a combined platform is worth considering.
Can we assess SME cash flow and repayment capacity from bank and accounting data?
Yes. HES LoanBox works with bank data pulled through open banking integrations, so
transaction history reaches the underwriting file without uploaded statements. Accounting
software is a separate case. Here the connection can be built as a custom integration, with
the effort depending on the borrower’s system and its APIs. Analysts read that data next to
credit bureau records to see how steady revenue is and what room is left for a new repayment
after existing obligations. With enough transaction history, a seasonal dip can be read as a
recurring pattern rather than a one-off drop, which matters most for young businesses with a
thin credit file. Which fields and indicators feed your underwriting rules or scorecards are
agreed upon during implementation, along with the providers for your market.
How long does SME lending software take to implement?
Two factors set the timeline: how much of the setup already exists, and what needs to be
built on top of your current system. Large enterprise suites often need a year or longer,
with internal IT and external consultants on the project until go-live. HES LoanBox starts
from a configurable core, so term loans and working capital lines are set up on existing
modules rather than coded from scratch, and the pre-built integrations include KYB and
payment providers. A standard SME launch takes from three months. Migrating an existing loan
book or opening several countries at once often extends the project past six months.
Accounting connections are built as custom integrations and planned separately. Discovery
fixes the scope before development begins.
Can we automate approvals for small-ticket SME loans while routing exceptions for manual
review?
Yes. As small business loan underwriting software, HES LoanBox sets the underwriting mode
per product group, so a small-ticket working capital product can run on automatic decisions
while larger term loans stay with an underwriter. You define the eligibility rules and score
cut-offs. Applications that clear them are approved with no manual step. Files where the
rules and the score disagree go to a review queue.
How much does SME lending software cost?
The total depends on the size of the book you plan to run and the amount of integration and
customization the project needs. Plenty of small business loan software is priced per user
or per active loan. That model works against SME lenders in particular, since small-ticket
portfolios grow in loan count much faster than in balance. HES LoanBox is licensed without
per-user fees, and adding staff accounts or borrowers leaves the license price unchanged.
Custom work is quoted separately. The final figure comes out of discovery, once the product
list and integration scope are agreed, with the platform cost and any build cost shown as
separate lines.
Does HES LoanBox integrate with our core banking and accounting systems?
It does. The platform is API-first, designed to sit alongside what a lender already runs,
core banking included. On the SME side it reaches business bureaus, sanctions and KYB
checks, open banking and accounting feeds, payment gateways, eSignature and document
handling, and BI tools, through more than 100 integrations, with open APIs for whatever is
bespoke. How much work it takes depends on your core and the number of neighbouring systems,
but the target never changes: data flows between systems on its own rather than riding
spreadsheets between desks.
How does HES LoanBox handle KYB for sole proprietors and incorporated businesses?
The split follows legal form, and verification runs through the KYC and KYB providers you
connect. A sole proprietor has no separate legal entity, so the workflow centers on the
owner: personal details plus the business documents you choose to request, such as a DBA
filing or a business bank statement. For LLCs and corporations, the form collects company
data and the people authorized to sign, then passes them to the KYB checks your provider
offers. How deep beneficial owner screening goes depends on that provider and the project
scope. Field lists and document rules are configured around your credit policy and local
requirements, and HES LoanBox logs application activity for audit review.