Buy Now Pay Later software
for digital lenders

HES LoanBox BNPL loan management software offers a dedicated engine that runs pay-in-4, deferred billing, longer installments, and B2B plans, configurable to your credit policy.
Book a demo
Buy Now Pay Later software
Integrations Pre-built integrations
Run identity checks, credit assessment, and approval inside a single automated flow so shoppers see a decision before they leave the checkout.
90%
faster loan approval
Score thin-file and repeat BNPL applicants with AI models that pull live data across merchants, baskets, and product categories to keep first-payment defaults down.
3x
scoring accuracy
Catch repayment risk earlier with predictive analytics that flag deteriorating cohorts before missed installments turn into write-offs.
40%
lower delinquency rates

Buy Now Pay Later software
for the complete customer journey

Instant onboarding

Deploy white-label BNPL software under your brand. Give shoppers a clear way to review terms and confirm identity without leaving checkout. The flow relies on real-time KYC checks and automated decisioning, with merchants connected through the API. Learn more

Accurate origination

Approve more customers using rule-based underwriting and real-time AI scoring on bureau and bank data. Set eligibility rules and promotional pricing per merchant, and cap limits by basket size or product category. Learn more

Transparent servicing

Administer installment schedules, payment retries, and buyer communications from a centralized workspace. Maintain full transparency across your BNPL portfolio with live repayment tracking and automated customer notifications. Learn more

Proactive collection

Recover outstanding balances more effectively with behavior-based payment reminders, early-stage risk signals, and adaptive repayment options that reduce friction and protect the customer relationship. Learn more

Get your lending
product estimate
in 3 minutes

STEP: /
BNPL digital onboarding

White-label BNPL software that turns intent
into approved purchases

Turn shoppers into approved buyers without losing them between cart and confirmation, giving them a fast, transparent path to installment payments.
BNPL widget on product page
instant BNPL approval at checkout
BNPL buyer self-service portal
BNPL merchant and POS partner portal

Hold attention from the product page onwards

An embedded BNPL widget shows split-pay options, installment amounts, and total cost directly on product pages and at checkout. Shoppers see the deal before they commit, which lifts conversion and cuts cart abandonment for higher-ticket items. BNPL widget on product page

Decide in seconds without losing the sale

Buyers enter minimal details, pass identity verification, and receive an approval decision before the checkout timer runs out. Your BNPL software handles soft credit checks and fraud signals automatically, keeping the purchase flow on a single screen. instant BNPL approval at checkout

Bring buyers back instead of chasing them

A self-service buyer portal shows upcoming installments, remaining balance, and one-tap repayment options. Automated reminders across SMS, email, and push reduce late payments, and a familiar interface turns first-time users into repeat shoppers across your merchant network. BNPL buyer self-service portal

Scale through merchant and partner networks

Onboard merchants, marketplaces, and POS partners with dedicated portals to manage their BNPL programs, track funded volumes, and access settlement data. Expand your BNPL platform footprint across new categories and geographies without rebuilding integrations. BNPL merchant and POS partner portal

Task management for
BNPL risk and merchant teams
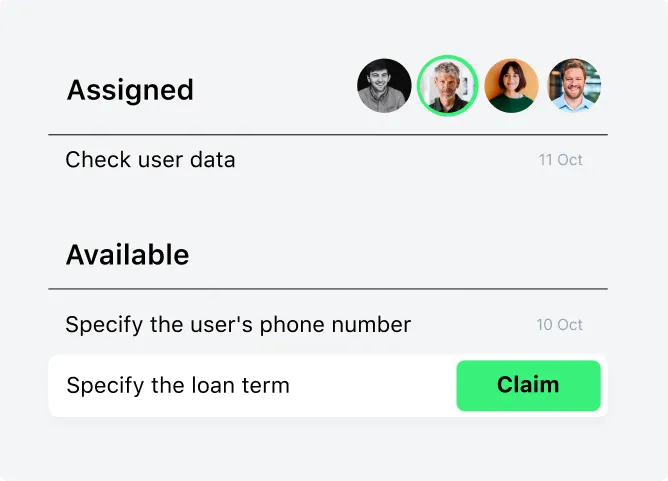
BNPL underwriting has to be fast enough for checkout and careful enough for first-time buyers with little credit history. HES LoanBox lets you choose how each program decides: credit rules, AI scoring, or both.
Learn more
BNPL task management dashboard
BNPL loan origination

Cut BNPL origination
time
with AI and
automation

Stalled checks and patchy first-time data quietly bleed conversion and inflate first-payment defaults. AI-driven verification and underwriting turn every Buy Now Pay Later application into a fast, confident, approval before the buyer clicks away.

Instant identity verification and buyer profiling

Run KYC and sanctions checks instantly, then enrich applications with credit and fraud signals. Get an audit-ready buyer profile before underwriting, even for first-time or thin-file applicants. BNPL identity verification and buyer profiling

Configurable underwriting at any speed

Approve purchases up to 90% faster with an underwriting engine tailored to your risk policy by merchant, product, and ticket size. Support fully automated pay-in-4, 24-month installments, or manual review for high-value cases without rewriting rules. configurable BNPL underwriting engine

AI credit decisioning that grows the basket

Choose the scoring approach that fits your lending strategy: use your own scorecard logic, the built-in AI engine, or run both side by side for shadow scoring. Improve risk assessment and reduce NPLs with more accurate scoring, while still supporting responsible lending to thin-file borrowers. AI credit decisioning for BNPL

Self-learning scoring by GiniMachine

GiniMachine learns from every funded BNPL plan, detecting shifts in defaults, fraud, and category risk before they impact your portfolio. Achieve up to 3x higher scoring accuracy than bureau-only models. GiniMachine self-learning AI scoring

Paperless from cart to confirmation

ID images, address proof, the credit agreement, and the affordability declaration get captured and signed inside the screen the buyer started on. Document handling costs drop by up to 90%, and the audit trail stays in one place instead of being scattered. paperless checkout with eSignature
identity verification and buyer profiling
configurable BNPL underwriting engine
AI credit decisioning for BNPL
GiniMachine self-learning AI scoring for BNPL
paperless BNPL checkout with eSignature
and much more

Configurable BNPL products

Launch BNPL products ranging from pay-in-3 and pay-in-4 to longer-term installments and B2B trade credit. Set pricing, fees, discounts, and eligibility rules for different markets, merchants, or campaigns without changing the code

Market-specific contracts

Generate BNPL agreements and disclosures from reusable templates, and apply market-specific wording to support multiple jurisdictions with no manual edits.

Message templates

Manage push notifications, emails, SMS, and other message types through configurable templates tied to key events such as approval, upcoming due dates, full repayment, or dispute resolution.

Role-based data access

Shopper data, merchant records, and partner portal access are protected by separate permission scopes, two-factor authentication, and role-based access controls. All user and system actions are logged to maintain a complete audit trail.

Adaptable BNPL workflows

Design BNPL approval paths, fraud decision branches, and settlement workflows on a visual canvas without developer involvement. Update workflows as risk conditions change and roll out new decision logic within days.

Automated communication

Keep buyers, merchants, and partners informed through SMS, email, in-app messages, and portals. Automated notifications reduce support inquiries and improve customer experience.

Configurable BNPL workflows

configurable BNPL workflow engine
BNPL loan servicing

Complete Buy Now Pay Later
loan servicing software

Spreadsheets, half-connected ledgers, and merchant settlement files in inboxes quietly drain margin out of every plan. Run BNPL servicing on a single live ledger with flexible terms, automated retries, and pre-integrated payment rails.
BNPL plan lifecycle automation dashboard
single workspace for active installment plans
BNPL buyer 360 view across merchants
merchant settlement and installment payments

Loan lifecycle automation

Run every BNPL plan from approval to final installment without touching a spreadsheet. Late fees, partial-refund recalculations, payment-method swaps, early-payoff discounts, and merchant-funded promotions all apply by your rules. The plan recalculates itself when a refund lands. BNPL plan lifecycle automation dashboard

Comprehensive loan management

Pay-in-4, longer installments, B2B trade credit, and zero-interest promotions live in one workspace. Reschedule, restructure, apply partial payments, or cancel a plan after a return, and the audit log keeps every change against the original purchase. single workspace for active installment plans

360° customer management (CRM)

See each buyer across every merchant they shopped: live and closed plans, baskets, repayment history, disputes, and risk profile. Support resolves queries without flipping tabs, and the system picks up returning shoppers before checkout instead of treating them as new. BNPL buyer 360 view across merchants

Trusted payment operations

Settle merchants, disburse plans, and collect installments across card networks, ACH, SEPA, direct debit, and local rails through pre-built integrations. Retries on failed cards follow rules you set per category, transaction matching runs against the plan, and PCI scope stays with your acquirer. merchant settlement and installment payments
GiniMachine

Scoring you can read behind
every BNPL decision

The engine learns from your own historical loan and repayment data. For every application it returns a repayment probability and a per-attribute breakdown of what drove the result. Borderline cases route to a credit officer, so the model informs decisions instead of making them.
Learn more
BNPL loan collection

Boost recovery on overdue
BNPL installments

Late installments on small tickets cost more to chase than they recover, and aggressive dunning sends shoppers to the next BNPL provider. Automate outreach with AI that picks who to contact, when, and how.

Automate the full recovery workflow

Move every overdue plan forward without manual work.
Reach buyers via push, in-app, SMS, email, and voice
Run pre-built or custom workflows by overdue stage and category
automated BNPL recovery workflow

Tailor every recovery action with AI

Adapt recovery actions to the buyer, repayment plan, merchant, and purchase category, using different outreach strategies for each shopper segment and prioritizing overdue installments with the highest recovery potential. AI-driven collections scoring

Prevent missed payments before they happen

A first missed installment usually predicts the pattern.
Schedule reminders before due date with plan-aware wording
Mix push, in-app, SMS, email, and merchant-portal alerts
proactive BNPL payment reminders

Configurable penalties with an audit trail

Apply overdue fees and interest within the limits each market sets, with audit-ready records for examination cycles.
Configure penalty rules per BNPL product, market, and category
Keep buyer correspondence transparent and every action audit-logged
configurable penalty rules per market
automated BNPL recovery workflow
AI-driven collections scoring
proactive BNPL payment reminders
configurable penalty rules per market

BNPL reporting and analytics

HES LoanBox builds interactive dashboards around the BNPL numbers your team actually opens: approval rate by merchant, AOV, first-payment defaults, and vintage losses. Drill in, export raw data, or layer custom metrics on top.
BNPL reporting and analytics dashboard

Why lenders choose HES

Fast, predictable launch

Go live with a BNPL product from three months. Detailed estimates and fixed-price delivery options provide up to 95% accuracy of the projects' budget before development starts.

Ready for merchant-led BNPL

Onboard merchants through dedicated portals, apply your branding across borrower and merchant interfaces, and support different currencies, payment rails, and market-specific product rules.

Built for lending

HES FinTech has been building lending software since 2012 for financial institutions across multiple markets, including consumer and short-term lending.

Configure, customize, or own the code

Configure product rules, pricing, eligibility, and workflows yourself, commission deeper custom development, or purchase a developer license with source code access when you need greater control over the platform.

Configurable controls

Pre-contractual disclosures, affordability checks, and cooling-off periods are configurable controls, and the platform keeps audit-ready records for the examination cycle.

Multi-currency handling you configure

Run BNPL programmes globally. Configure currency handling, local payment-rail routing, and jurisdiction-specific fee structures.
Success stories

client
HES FinTech has been our reliable technology partner since 2012. I believe much of our success is due to the well-architected HES LoanBox solution.
photo
Boris Batine
Co-Founder, ID Finance
client
HES FinTech offers comprehensive front-to-back solutions with integrations. Our machine learning platform will allow clients best-in-class investment advice.
photo
Edward Downpatrick
Strategy Director, Fintuity
client
In just 6 months, we went from storing all our data in Excel to a fast, reliable, and user-friendly platform that caters to our specific needs.
photo
Hjortur H. Jonsson
Partner, ALM Securities
client
HES FinTech developed our lending software and predictive analytics. Their expertise delivered automation, clear UI/UX and customer portal.
photo
Mazen Alasnag
Head of Loan Management, Wa'ed
client
The LMS provided flexible repayment options, automated restructuring and branch-level management, enhancing efficiency and risk mitigation.
photo
Urnukhjargal Badam
CEO, Tavan Bogd
Security
Deployment
Tech stack

Enterprise-grade
BNPL security

ISO 27001-certified and SOC 2-aligned, with an SDLC built around consistent security, full data encryption, role-based access, and hardened hosting for shopper and merchant data on every BNPL deployment.
Learn more

Deploy where
your team prefers

Run HES LoanBox in the cloud of your choice, on-premises, or as a hybrid setup, with AWS and Google Cloud supported out of the box.
aws

Open-source
backend foundation

Java LTS, BPMN 2.0, Camunda, and Form.io modeler form the open-source backbone of HES LoanBox. No licensing fees pile up beyond the platform source, so cost stays flat as your BNPL program grows across markets.
HES LoanBox BNPL technology architecture

BNPL in
2026

$300B
Global BNPL transaction value in 2025
Global BNPL transaction value reached approximately $342 billion in 2024 and is projected to hit $500 billion by 2030. Growing transaction volumes put more pressure on lenders to scale decisioning, servicing, and payments without adding the same level of operational overhead.
26%
of U.S. BNPL users paid late
Federal Reserve data shows that 26% of U.S. BNPL users made a late payment in 2025. As BNPL portfolios grow, accurate affordability assessment and early identification of repayment risk become more important.
2026
UK BNPL regulation takes effect
The FCA began regulating qualifying third-party Deferred Payment Credit on 15 July 2026. The rules introduce affordability checks, Consumer Duty requirements, and clearer information for borrowers before they enter into an agreement.
25%
of BNPL users have held 3+ loans at once
A 2026 LendingTree survey found that 25% of BNPL users had held three or more BNPL loans simultaneously. Multiple active plans make borrower exposure harder to assess from a single application and increase the importance of current borrower data and flexible scoring.

Launch BNPL
from 3 months

Bring the merchants and shoppers, HES LoanBox brings the platform.
Book a demo

FAQ

Who is HES LoanBox BNPL suite for?

HES LoanBox for BNPL is built for organizations that run their own buy now pay later program and want to set the pricing and keep the borrower relationship themselves, rather than pass it to an external BNPL provider. In practice, that covers five groups.

1. BNPL fintechs launching a pay-in-4 or installment product, or moving an existing book to a new platform.
2. Banks and credit unions adding installment options to cards and current accounts, so customers split purchases inside the bank’s own app.
3. Payment providers and acquirers offering white-label BNPL to merchants already on their network.
4. Retailers and marketplaces that want a branded installment plan with their own credit rules.
5. B2B lenders extending pay-later terms to companies rather than shoppers.

Shoppers who want to split a purchase need a consumer BNPL provider.

Does HES FinTech provide BNPL to consumers or the software to launch it?

HES FinTech does not lend to shoppers and is not a BNPL provider. We build the software that banks, fintechs, payment companies, and retailers use to run their own buy now pay later programs under their own brand. You set the credit policy and hold the loan book, along with the customer data and merchant relationships. The platform supplies the engine underneath: checkout widget, decisioning, servicing, and collections.

The difference matters commercially. With a pure-play BNPL network, you rent their balance sheet, their rules, and their take rate. With buy now pay later software, the program is yours end-to-end, and so is the margin. That is why our clients are lenders and platforms launching BNPL, not consumers looking to split a purchase.

Should I buy BNPL lending software or build it in-house?

Build only if BNPL technology itself is your competitive edge and you can fund a team to maintain it for years. A working stack covers the checkout widget, real-time decisioning, plan servicing, collections, payment rails, and fraud checks, and each part needs updates as scheme rules and regulation change (in the UK, FCA rules for BNPL apply from July 15, 2026). For most lenders, that means several quarters of engineering before the first plan is funded.

If your edge is the credit program, meaning pricing, risk appetite, merchant relationships, and the customer experience, buying is usually faster. You configure products and rules on a platform that already runs in production, and your engineers work on checkout UX and your own risk models.

Some lenders take a middle route. HES LoanBox gives you a configurable core, and if you want full control, the license and source code can be transferred so your team extends the platform in-house. Simpler programs go live from three months; complex ones take longer.

How do I choose a BNPL loan management solution?

Start with your program model. A direct pay-in-4 product and B2B trade credit sold through merchants need different things, so the model decides what you ask the vendors on your shortlist.

1. Which product and rule changes can your team make without a vendor release? Ask to see a new plan type configured live.
2. How fast does a decision come back inside checkout, and which thin-file data can you connect?
3. What happens to an active plan after a partial refund or a dispute? Check merchant settlement too.
4. Can your scorecard run next to the vendor's model, so you compare first-payment defaults on your own applications?
5. Where are affordability checks and fee caps set for each market, and what records does your compliance team get?
6. What will you pay at your target volume? On small tickets, per-loan fees often outweigh per-seat pricing.
7. If you leave, how do you take your data, and can the source code be transferred?

If most answers point to configuration, you can launch without waiting on the vendor's roadmap. A custom build is still reasonable provided the vendor answers the rest well.

HES LoanBox runs standard BNPL models on no-code settings and adds custom logic on the same platform when needed. Launch takes from three months, depending on scope. Users are unlimited, so pricing does not rise with headcount, and source-code ownership is available as an option.

How are merchant settlements and refunds handled?

HES LoanBox runs merchant settlement as a configurable workflow, with payout timing and fee deductions set per merchant and funds moving through the payment providers you connect. You also set the refund rules: once the merchant confirms a full or partial refund, the plan is recalculated on the lower balance or closed, and anything the shopper overpaid goes back through the same provider. On the settlement side, the refunded sum can be netted from the merchant’s next payout. Adjustments stay tied to the original plan and order reference for reconciliation and audit review. How much runs without manual steps depends on your merchant integrations and payment provider.