End-to-end commercial lending software for banks, credit unions, and alternative lenders. Run each loan
on one business lending software platform, from onboarding and underwriting to collections.
Commercial lending automation runs credit workflows and multi-party approvals as configured
processes, cutting rekeying and manual handoffs, so each commercial loan costs less to
close.
60%
cost reduction
Commercial credit analysis pairs analyst review of borrower financials and sector exposure
with AI scoring of payment behavior. Risk ratings gain precision and trace back to source
data.
3x
scoring accuracy
Support commercial loan growth without scaling your back office. Automation handles
origination, documentation, and portfolio monitoring across every stage of the lending
cycle.
10x
capacity
Commercial loan origination software
for the full commercial lending lifecycle
Structured onboarding
Run the commercial online application through a branded borrower portal built for multi-entity
structures and document-heavy intake. Configure KYB and sanctions screening to fit your process.
Learn more
Disciplined origination
Make credit decisions on complex commercial facilities with configurable underwriting workflows
and third-party data integrations. Structure deals around custom covenants and collateral
conditions by sector and facility type.
Learn more
Portfolio servicing
Handle drawdowns and repayment cycles from one workspace in the commercial loan servicing
software. Track exposure across the commercial loan book with covenant monitoring and breach
alerts.
Learn more
Active collection
Detect financial stress across the commercial portfolio with predictive risk analytics before
payments slip. Engage borrowers early through structured workout and restructuring options,
backed by escalation workflows.
Learn more
Get your lending
product estimate in 3 minutes
STEP:
/
Online onboarding
Commercial loan origination software that turns deals into funded
facilities
Borrower and agent applications enter the commercial loan origination software through one
structured digital intake, beside leads your relationship managers add themselves. Document requests
go out with the application, so commercial deals reach underwriting with complete files.
Configurable application forms ask for the right financials, ownership disclosures,
and collateral details based on the facility type your borrower is requesting.
Analysts open every deal already structured for spreading, instead of chasing
missing tax returns.
Pre-qualify deals before underwriting starts
Configurable pre-qualification rules filter incoming commercial applications against
your credit box, geography, industry exclusions, and minimum DSCR thresholds.
Underwriters stop wasting afternoons on deals that were never going to fund, and
brokers get instant feedback on what fits.
Run every deal from one live workspace
The white-label HES LoanBox borrower portal brings clients, guarantors, your
relationship manager, and credit analyst into a shared deal room with
version-controlled documents, structured questions, and one status timeline. Email
chains, lost attachments, and conflicting term sheet drafts disappear for good.
Track broker and partner deal flow
Brokers, CPAs, and referral partners submit deals through their own branded portal
with live status tracking, document checklists, and clear submission standards.
Backed by 100+ integrations, third-party channels become a measurable source of
funded commercial volume, not a black box.
Commercial loan processing software with smart task routing
Within the commercial loan processing software, each facility is assigned to the right relationship
manager, credit analyst, or credit committee member by workload and expertise. Aging deals and
overdue tasks surface early, so the team closes more applications without adding headcount.
Cut commercial loan
origination time
without cutting
underwriting depth
HES commercial loan origination platform combines AI-driven verification, financial spreading, and
configurable underwriting, so each commercial application ends in a fast decision with an
audit-ready record.
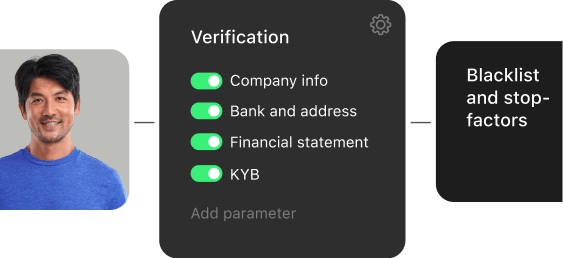
Run KYB, sanctions, and UBO checks against the full ownership chain in seconds, then
enrich every application with business credit bureau data, open banking cash flow
signals, and prior banking history. Analysts draft the credit memo from a complete,
audit-ready borrower file before the first committee meeting.
Configurable underwriting for every deal size
A single commercial loan underwriting software engine handles small business deals
through full auto-decisioning, mid-market facilities through hybrid workflows, and
complex CRE deals through full committee review.
AI credit decisioning for more approvals
Combine your own scoring rules with AI-powered decisioning trained on commercial
portfolio outcomes. Configure custom scorecards or plug in the built-in AI engine to
approve more facilities, cut NPLs by up to 40%, and confidently underwrite
businesses competitors mark as too thin.
Self-learning scoring by GiniMachine
GiniMachine’s AI scoring engine trains on your portfolio’s repayment history. Each
application gets a probability of repayment and a resolution, while self-learning
models update on new outcomes and give your credit team up to 3x scoring accuracy.
Paperless from term sheet to signature
Eliminate paperwork at every step with built-in commercial loan documentation
software, cutting document handling costs by up to 90%. OCR extracts and validates
tax returns, financials, and corporate documents in seconds, while connected
eSignature tools close commitment letters and security agreements remotely.
and much more
Unlimited product configuration
Launch any commercial credit product, from term loans and lines of credit to CRE facilities,
asset-based lending, SBA loans, or working capital. Configure loan pricing, fees, covenants,
collateral types, and amortization per product without code.
Automated document generation
Generate commitment letters, security agreements, and guaranties in seconds using dynamic
templates with merge variables. The commercial loan document software keeps each template
aligned with your credit policy and jurisdiction.
Multichannel borrower communication
Coordinate outreach across email, SMS, and in-portal channels with rule-based triggers tied
to deal status and covenant events. Keep CFOs, controllers, brokers, and your relationship
managers in sync without flooding inboxes or losing context.
Smart notification templates
Build personalized email and SMS templates with dynamic variables for borrowers and
partners, from covenant compliance deadlines to drawdown notices, maturity and renewal
alerts, and annual credit review prompts.
Role-based security and access control
Protect borrower financials with granular role-based permissions, separation of duties
between origination and servicing, two-factor authentication, and a complete audit trail of
user activity that auditors and examiners can review.
No-code workflow builder
Design and modify lending workflows visually, with no developer involvement. Adjust
underwriting paths, approval logic, and committee routing as your credit policy evolves, and
launch new product lines in days, not quarters.
Business lending software with configurable workflows
Commercial loan servicing
Commercial loan servicing software for your entire loan book
Commercial loan software keeps covenant data, flexible amortization terms, and payment rails in one
place, so servicing runs without manual reconciliations between systems. Track exposure on each
facility with real-time data.
Each commercial facility runs from first drawdown to payoff under your credit policy
rules. Interest accruals, unused commitment fees, prepayment penalties, and
restructurings process in the platform, with no spreadsheet reconciliation.
Multi-facility loan management
Manage term loans, revolvers with borrowing base, CRE facilities, syndicated
participations, and equipment finance from a single commercial loan management
platform. Adjust schedules, apply covenant waivers, process partial paydowns, and
restructure terms while preserving full audit history for examiners.
360° relationship management
See every commercial borrower in one place: linked entities, every active facility,
guarantor exposure, covenant track record, payment history, and CFO communications.
Your relationship managers spot cross-sell opportunities early and catch covenant
trouble before it becomes a workout.
Trusted payment operations
Process disbursements and repayments through SEPA, SWIFT, ACH, card networks, and
any payment provider via open API. Every transaction matches the right facility
automatically, posts to borrower records in real time, and stays fully auditable.
Maximize commercial loan portfolio
performance with AI risk intelligence
AI-driven risk precision
Sharpen decisions with AI scoring built into the commercial credit software, delivering up
to 3× better accuracy than traditional underwriting models.
Smarter risk control
Flag deterioration with custom risk thresholds in the commercial loan portfolio management
software, then reprice or adjust limits before covenants break.
Scoring made clear
Apply predictive scoring from origination screening to covenant monitoring and loss
forecasting, with explainable outputs examiners can follow.
Commercial loan collections
Recover more with proactive
commercial workout and collections
Manual workouts move slowly and burn senior credit hours that should fund new deals. Automate early
warning, restructuring, and recovery actions with AI tools that flag deterioration early, prioritize
cases, and stay defensible across every commercial facility.
Move troubled facilities through workout with less manual effort. Multi-channel
outreach reaches the CFO and guarantors from one case file, and workout notices and
waiver agreements go from template to signature inside the platform. Assign a
pre-built or custom strategy to each risk segment.
Tailor every workout action with AI
Recovery strategies are set at deal level, with communication paths matched to
borrower size and segment. Let AI inform when to reach out or escalate to committee
review, and rank high-recovery exposures first with AI/ML collection scoring. Each
borrower’s predicted repayment probability also feeds a forecast of portfolio cash
inflows.
Catch covenant trouble before it costs you
Problem credits show up early because monitoring runs continuously across the
commercial book. Configure custom alerts for covenant breaches and late financial
statements, and track deterioration and payment delays next to risk rating changes.
When a facility needs attention, follow up by email, SMS, voice, or in-portal
message.
Manage workouts with full audit confidence
Run restructurings and waivers through configurable rules tied to your credit
policy, with penalty terms that differ by product and jurisdiction. Fee caps and
approval thresholds are set once and hold across the portfolio. Keep borrowers
informed throughout, while every workout action leaves an audit-ready trail you can
defend in the next examination cycle.
Commercial lending reporting and analytics
As a commercial loan reporting platform, HES LoanBox turns your credit and portfolio KPIs into
interactive dashboards. Configure custom metrics by industry, product, or risk grade, and export raw
data for your own stress testing.
100+ integrations to power up your commercial lending platform
HES LoanBox connects to a broad ecosystem of integrations across onboarding, business credit
bureaus, payments, document signing, communication, analytics, and core banking. Flexible APIs and
full customization let you fit the platform into the commercial lending systems you already run.
What you get with our
commercial lending platform
Unlimited customization
Tailor modules, build out custom workflows, design approval routes for your credit
committee, and connect any service from business credit bureaus to your core banking stack.
Transparent pricing
HES offers simple pricing: you pay for the license, with extra for custom development.
Unlimited users and borrowers included. Developer license available for full control and no
vendor lock-in.
Industry expertise
Work with business analysts from a lending-software team with 14+ years in the field and
160+ deployments in 32 countries, from the US and EU to emerging markets.
3-month product launch
Go live from 3 months. Start booking commercial deals fast and reach ROI far sooner than
legacy commercial lending software solutions typically allow.
Proven security
ISO 27001 certified and SOC 2 aligned. Hosted on AWS or Google Cloud with a secure Java LTS
stack, role-based access, and audit logs.
Dedicated support
Get fast, expert help from our dedicated commercial support team whenever you need it.
Success stories
HES FinTech has been our reliable technology partner since 2012. I believe much of our success is due to the well-architected HES LoanBox solution.
HES FinTech is ISO 27001 certified and has completed an independent SOC 2
examination, with full data encryption, role-based access control, and
secure hosting behind each deployment.
HES LoanBox can be deployed on-premises, in the cloud of any chosen provider
(AWS, Google Cloud), or hybrid.
Open-source backend tools
HES FinTech builds solutions using free and open-source solutions, like Java
LTS, BPMN 2.0, Camunda, and Form.io modeler. This approach allows us to
exclude any additional licensing fees, except for the platform’s source
code.
2026 data
on commercial lending
$1.14T
NDFI commercial loan exposure
US bank commercial loans to non-depository financial institutions hit
$1.14 trillion
by early 2025 (Federal Reserve, 2025). Hidden risks in opaque commercial books are now
front-page news.
1.86%
CRE delinquencies at top-100 banks
Commercial real estate delinquency
at the largest US banks climbed to 1.86% in Q3 2025, up 23% year-over-year (Federal Reserve,
2025). Manual covenant tracking cannot keep up.
46%
SMB applications with fraud signals
46% of small business loan applications
showed signs of first-party fraud, and 80% of fraud events now occur on digital channels
(Experian, 2025). KYB cannot be optional.
70%
of bank IT spend trapped in legacy
70% of bank IT budgets
go to maintaining legacy systems instead of innovation (McKinsey). Modernization has become
a crucial question for such institutions.
Start lending from 3 months
While you focus on deals, HES FinTech handles the platform.
Commercial lending software, also called business lending software, manages credit extended
to businesses rather than individuals. That difference shapes the design. Banks and credit
unions use it, as do non-bank lenders, to run the full life of a business loan from the
online application and credit analysis to final payoff or workout. A business application
arrives with ownership structures and financial statements. The facility that follows
carries covenants and collateral, often across several linked entities, and its document
management and portfolio monitoring continue for years after funding.
How does commercial lending software handle covenant monitoring?
In commercial loan servicing software, covenant monitoring follows the terms of each loan
agreement: financial thresholds such as minimum DSCR or maximum debt-to-EBITDA, plus testing
dates and reporting deadlines. Financial tests run on updated borrower data and check
compliance against the agreed definitions and limits. Configured workflows remind designated
borrower contacts when financial reports are due and flag overdue submissions or potential
breaches to the lending team as open exceptions. Relationship managers can review covenant
compliance history alongside payment performance. Approved waivers and amendments go on
record against the relevant facility, which keeps the audit trail intact for annual credit
reviews and renewals, as well as any later restructuring or workout.
How quickly can a commercial lending platform go live?
From 3 months for a focused launch on HES LoanBox: term loans, lines of credit, or CRE
facilities set up as configurable products and workflows, connected to the usual
integrations such as KYB providers and payment gateways. Migrating open facilities usually
takes longest, since their covenant history has to arrive intact. Heavy custom work with
multiple loan products, several jurisdictions, or unusual regulatory requirements may take
up to 6 months. Legacy commercial lending platforms often need 12 to 18 months to implement,
plus in-house IT staff and consultants for the length of the project.
How does commercial lending software help with credit risk and regulatory compliance?
Credit risk and compliance work together in commercial lending, and modern commercial credit
software treats them as one workflow rather than two. The platform centralizes borrower
financials, exposure tracking, and AI-driven scoring across the full commercial loan
portfolio, so credit teams see deterioration weeks before a manual review would catch it.
Also, the platform logs user actions and keeps tracked documents, while role-based
permissions enforce separation of duties between origination and servicing. HES FinTech is
ISO 27001 certified and has completed an independent SOC 2 examination. These controls help
meet regulatory expectations, and the records stay available for examiners, so your team can
show how a specific deal was approved.
Can commercial lending platforms handle CRE, C&I, and SBA loans in one system?
Yes, as long as the product engine is configurable and not hard-coded per loan type. C&I
term loans and revolving lines run next to CRE facilities and SBA loans as separate products
on one platform. Each gets its own rates, fees, covenants, collateral types, and
amortization schedules. For property-secured deals, the same system acts as commercial real
estate lending software: configurable forms capture property performance and tenant quality
data at underwriting. Once the loan funds, it works as commercial mortgage servicing
software. SBA-specific requirements (guaranty documentation, program reporting) are scoped
during implementation, not assumed in the demo.
How much does commercial lending software cost?
HES LoanBox pricing is a license fee plus any custom development you order, with no cap on
users or borrowers. Product and workflow configuration is covered by the platform itself,
which leaves custom work as the part of the budget that varies. Lenders that want to control
the code themselves can take a developer license.
How are broker-introduced commercial deals handled?
A broker, or a referral partner like a CPA, sends deals in through a branded partner portal
that lists the documents each facility type needs and shows live submission status.
Pre-qualification rules screen the deal against your credit box (industry exclusions, a
minimum DSCR). The broker learns early whether it fits. Accepted deals enter the same
origination flow as direct applications, under one credit policy. Reporting then shows which
partners bring funded volume and which mostly send raw leads.
Does HES LoanBox integrate with our core banking system?
Yes, that is the usual setup. HES LoanBox is API-first and built to integrate with the
systems banks and non-bank lenders already run. Payments can run over SEPA, SWIFT, ACH or
card networks, with each one matched to its facility as it posts. For UK lenders, a single
Acquired integration covers collections by card, Direct Debit, open banking and Variable
Recurring Payments, plus instant payouts for disbursements. The lender picks the method per
borrower or product. The library of 100+ integrations takes in business credit bureaus,
sanctions and KYB checks, payment gateways, e-signing, accounting and ERP packages, and BI
tools. Anything outside the library connects over the open API.
Book a demo
HES FinTech has been our reliable technology partner since 2012. We owe much of
our success to their well-architectured solution.
Boris Batine, CEO at ID Finance
HES FinTech offers comprehensive front-to-back solutions with integrations. Our
machine learning platform will allow clients best-in-class investment advice.
Edward Downpatrick, Strategy Director at Fintuity
In just 6 months, we went from storing all our data in Excel to a fast,
reliable, and user-friendly platform that caters to our specific needs.
Hjortur H. Jonsson, Partner at ALM Securities
HES developed our lending software and predictive analytics. Their expertise
delivered automation, clear UI/UX, and customer portal.
Mazen Alasnag, Head of Loan Management at Wa’ed
The LMS provided flexible repayment options, automated restructuring and
branch-level management, enhancing efficiency and risk mitigation.