Built for lenders, FCA-authorised banks, building societies, and BNPL providers. A single platform for
Open Banking, Consumer Duty compliance, and full loan servicing.
Consumer Duty puts every line of the price-and-value assessment under review. Paperless
applications and eSignature take most of the handling cost out of each file.
90%
lower document handling costs
Build your scorecards and tune them as your book evolves. Run GiniMachine AI scoring
alongside them: the engine trains on your repayment history and can cut NPLs by up to 40%.
3x
scoring accuracy
Affordability files, FOS complaint packs, vulnerability assessments. Strip rekeying out of
these workflows so underwriters and agents spend hours on judgement, not admin.
44%
staff efficiency
Loan management software
across the lending lifecycle
FCA-ready onboarding
Launch a white-label borrower journey for consumer credit, motor finance, or BNPL applicants.
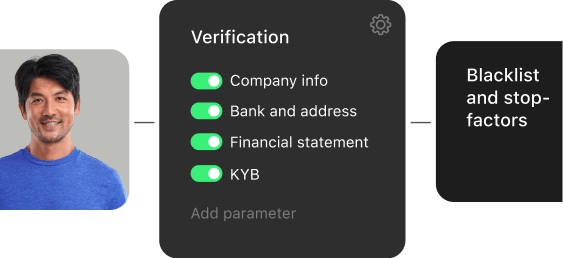
Collect data once, plug in your preferred KYC and KYB providers, and capture risk indicators on
the application before underwriting picks up the file.
Learn more
Configurable origination
Run CONC-aligned creditworthiness checks against Open Banking data, Experian, Equifax, and
TransUnion in one underwriting pass. Configure rules, pricing, and contract templates for
personal loans, bridging finance, asset-based deals, or BNPL without rebuilding the journey each
time.
Learn more
End-to-end servicing
Run repayment schedules across Direct Debit, Bacs, and Faster Payments with full ledger
visibility. Process FCA forbearance, payment holidays, and rate switches without spreadsheets,
and leave an audit-ready trail through every customer touchpoint.
Learn more
Arrears management
Recover arrears under FCA forbearance expectations with profile-based segmentation tuned for
delinquency stage, multi-channel outreach, and AI scoring that suggests the right strategy for
each UK borrower in payment difficulty.
Learn more
Get your lending
product estimate
in 3 minutes
STEP:
/
Online onboarding
Digital lending onboarding built for UK regulatory expectations
HES LoanBox takes applicants from first click to signed agreement without losing them to long forms
or unclear pricing. Capture the data underwriters need, log every step, and free your team from
rekeying applicant details between systems.
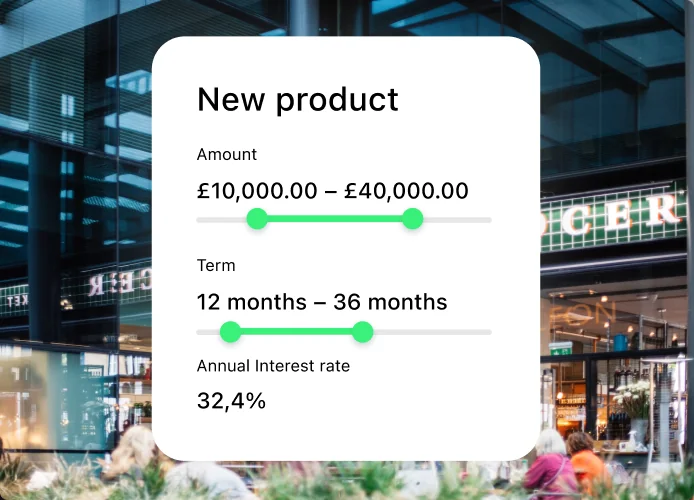
An embedded affordability calculator lets UK applicants test amounts, terms, and
monthly repayments against representative APR. Showing a clear total cost before the
application starts cuts drop-off, supports Consumer Duty understanding outcomes, and
stops surprises after credit search.
Decide faster without skipping checks
Applicants enter details, share Open Banking data, upload documents, and sign the
pre-contract information form from any device. Identity, affordability, and
creditworthiness checks run in parallel, cutting decision time from days to minutes
without weakening the CONC trail.
Stay close to borrowers after drawdown
A self-service portal lets UK borrowers view the schedule, check balance, switch
payment date, and submit a forbearance request without ringing the office. SMS and
email reminders cut missed Direct Debits, and every interaction lands on the audit
trail.
Scale through brokers and introducers
Give brokers, introducers, and appointed representatives a branded portal to package
applications and watch decision status in real time. Track submissions, approval
rates, and channel performance from one dashboard without standing up a separate
broker management system.
Smart task management for UK lenders
HES LoanBox keeps every file moving from application to final repayment. Match work to the right
desk by case type, watch SLAs against drop-off targets, and align underwriters, credit officers, and
collections agents on one queue.
Manual rekey and stale bureau pulls add weeks to UK consumer credit decisions. Live Open Banking,
OCR on payslips and P60s, and eSignature turn every application into a fast, CONC-grade call and cut
document handling costs by up to 90%.
Run KYC, AML, and biometric checks in seconds, then enrich each application with
Experian, Equifax, or TransUnion data, Open Banking transactions, and Companies
House records for self-employed applicants.
Underwriting that matches your risk policy
Approve loans up to 80% faster with an underwriting engine configured to your CONC
5.2A policy. Run applications fully automated, hybrid, or manually depending on
product, ticket size, or risk band, without dropping conversion or the compliance
line.
Approve more good risk
Build your own scorecards from scratch, rule by rule, and tune them as your book
evolves. Or switch on
GiniMachine AI scoring, the engine inside HES LoanBox that learns from every credit decision, lifting
accuracy up to 3× versus bureau-only models. Either path cuts NPLs by up to 40%.
And other loan origination features
Unlimited product range
Run any lending product on the same core, from personal loans to motor finance, and BNPL.
Configure rates, fees, repayment schedules, and eligibility rules without raising a
developer ticket.
Customisable application flow
Design lending workflows visually, with no developer queue between you and production. Map
approval gates and decision trees, then launch a new product without a development cycle
when rules change.
Roles-based access
Protect borrower data with role-based permissions, password policies, two-factor
authentication, and device-level rules. Every user action lands on an audit trail ready for
FCA and GDPR review.
Compliant agreements in seconds
Generate legally binding loan agreements in seconds from dynamic templates. Pre-contract
information forms, credit agreements, and schedules pull together, with wording aligned to
UK consumer credit expectations.
Configurable lending workflows for UK lenders
UK loan servicing
Complete UK loan management software
Servicing in Excel and three half-connected legacy tools quietly eats margin and credibility. HES
LoanBox keeps every loan in one system, from drawdown to final repayment, so the ledger stays
current as payments come in.
Run every loan from drawdown through final settlement on configurable workflows.
Interest accruals, default fees, restructuring, refinances, and early settlement
quotes execute by your rule book, while one borrower record holds applications,
active loans, and complaints together.
Configure changes on the fly
UK forbearance and Consumer Duty mean loans rarely stay as written. Configure the
flexibilities your borrowers actually need: payment holidays, term extensions, rate
switches, partial payments, or restructuring, and your team applies them in minutes
with every change on the audit trail.
Payments on UK rails
Connect to Direct Debit, Bacs, Faster Payments, CHAPS, and card rails through
provider integrations. Schedule disbursements, reconcile repayments automatically,
and keep PCI scope with your acquirer where it belongs.
Strengthen your loan portfolio performance
with AI risk intelligence
Explainable scoring for FCA review
Apply predictive scoring across the UK lending journey, from pre-screening to NPL
forecasting, with reason codes both credit committee and FCA supervisor can follow.
AI accuracy at scale
AI scoring trained on your portfolio lifts accuracy up to 3× versus bureau-only models by
reading live transactions, instead of three-month-old credit files.
Risk-based pricing controls
Set thresholds by segment, spot affordability stress before arrears, and re-price as the
2026 refinance wave reshapes UK borrower cashflow.
Debt collection
UK debt collection software
powered by AI
FCA enforcement on vulnerable customers and Consumer Duty support outcomes turn every UK arrears
case into a compliance event. HES LoanBox routes accounts through workflows tuned for affordability,
vulnerability signals, and the rate caps your permissions allow.
Cut manual chase work and move every arrears case forward without bottlenecks.
Run multi-channel outreach across SMS, email, voice, WhatsApp, and outbound
dialler
Apply pre-built or custom workflows by delinquency bucket and product
AI-tuned strategy for each case
Drop one-size-fits-all dunning for borrower-specific recovery strategies tuned by
behaviour.
Pick the best communication sequence to increase positive responses
Use AI to optimise timing, channel, tone, and message wording
Score the arrears book and prioritise cases with real recovery odds
Forecast cash inflows and write-off exposure for the next IFRS 9 cycle
Fee and interest charges under FCA limits
Apply overdue fees and interest within caps you configure for each product.
Configure fee and interest rules by product
Keep transparent borrower correspondence and an audit trail ready for FCA
review
Lending reporting and analytics
HES LoanBox builds interactive dashboards around the lending KPIs your credit committee and CFO
actually open. Export raw data for FCA reporting, configure custom metrics, and slice the portfolio
by product, channel, or vintage.
100+ UK and international integrations to power up your lending
stack
HES LoanBox connects to the lending stack your team already uses. Add the UK services you need:
credit bureaus such as Experian, Equifax, and TransUnion, Open Banking providers such as TrueLayer
or Yapily, Bacs and Faster Payments through your payment provider, plus your KYC, accounting, and
core banking tools.
What UK lenders get
by choosing HES LoanBox
Customisation without lock-in
Tailor modules, adjust the borrower journey, and integrate with any UK service from Open
Banking to payment rails, with no vendor lock-in.
Transparent pricing
Pay for the licence, with extras only for custom build. Unlimited internal users, brokers,
and UK borrowers are included, with no per-seat fees as your portfolio grows.
3-month launch for UK lenders
Go live from 3 months on a standard configuration. Start lending in the UK fast, see ROI
sooner, and keep adjusting the platform as your book grows.
Lending expertise & dedicated support
Get fast help from a dedicated business analysts and engineers who have built and run lending products for over a decade.
ISO 27001 certification, SOC 2 alignment, and SDLC controls keep security
tight across every operation, with full data encryption, role-based access,
audit trails ready for FCA review, and a hardened hosting setup.
HES LoanBox deploys on AWS, Google Cloud, on-premises, or in a hybrid setup,
matching your IT estate and your board's data preferences.
Open-source backend stack
HES LoanBox runs on free and open-source foundations like Java LTS, BPMN
2.0, and Form.io modeler. No licensing fees beyond the platform source code,
and source code ownership is available as an option.
The 2026 reality of
UK lending
1.8M
UK mortgages expiring in 2026
UK Finance forecasts
1.8 million deals
ending through 2026. The lenders that win this volume will be the ones whose underwriting
runs in minutes, not weeks.
£600M
stolen by fraud in H1 2025
Fraudsters made off with
over £600 million
in H1 2025, with APP fraud up 12%. Layered digital identity, Open Banking, and device
signals stop more before drawdown.
Jul ’26
BNPL under FCA rules
Since
15 July 2026, third-party BNPL lenders have needed FCA authorisation and creditworthiness checks.
Running those checks at checkout without losing the sale takes automated affordability
decisioning.
8.5%
annual growth in UK consumer credit
UK consumer credit is growing at
8.5% year-on-year
(Bank of England). Loan books expand faster than headcount, so the cost of every decision
has to come down.
Start UK lending from 3 months
While you focus on UK growth, HES LoanBox handles the rest.
Can HES LoanBox integrate with our existing loan management systems in the United
Kingdom?
Yes, HES LoanBox is designed for seamless integration with your existing systems. It
supports API connections to UK KYC providers, British credit bureaus, UK open banking
platforms, and other essential financial services, ensuring a smooth and efficient workflow
for UK financial institutions.
What makes your loan management software specifically tailored for the UK market?
Our platform is designed with flexibility to support all UK lending requirements. HES
LoanBox is configured to handle FCA compliance workflows and can be connected with major UK
services like Experian, Equifax, TransUnion for credit data, Open Banking providers such as
TrueLayer, Tink, or Yapily, and other financial services. The system can incorporate
affordability assessments and regulatory reporting exports. What sets us apart is our
adaptability. We can customise integrations and workflows to match your specific UK
compliance requirements and preferred service providers.
Which types of UK lending services does HES LoanBox support?
HES LoanBox supports a range of UK lending models. Whether you're focused on personal loans,
guarantor lending, payday loans, bridging finance, asset-based lending, or peer-to-peer
lending, HES LoanBox can be adapted to support your specific approach. We've designed the
system to be flexible across different lending scenarios, from smaller consumer credit
operations to larger commercial finance deals. The platform's modular architecture allows us
to configure workflows, risk assessment tools, and compliance features to match whatever
lending services your business provides in the UK market.
Book a demo
HES FinTech has been our reliable technology partner since 2012. We owe much of
our success to their well-architectured solution.
Boris Batine, CEO at ID Finance
HES FinTech offers comprehensive front-to-back solutions with integrations. Our
machine learning platform will allow clients best-in-class investment advice.
Edward Downpatrick, Strategy Director at Fintuity
In just 6 months, we went from storing all our data in Excel to a fast,
reliable, and user-friendly platform that caters to our specific needs.
Hjortur H. Jonsson, Partner at ALM Securities
HES developed our lending software and predictive analytics. Their expertise
delivered automation, clear UI/UX, and customer portal.
Mazen Alasnag, Head of Loan Management at Wa’ed
The LMS provided flexible repayment options, automated restructuring and
branch-level management, enhancing efficiency and risk mitigation.