Made for green lenders, solar and EV financiers, and bank green lending teams. Confirm green-asset
eligibility, fund the project, and track impact on one platform.
Newer green asset classes have thin repayment history, so decisioning draws on how loans in
your book actually performed, not a fixed rule.
3x
scoring accuracy
Volume can climb without the team climbing with it, because each green application runs from
eligibility check to payout on its own.
10x
lending capacity
What used to pile up as paper, eligibility proof, asset specs, subsidy forms, now gets
captured and verified digitally as the file moves.
90%
less paperwork
Green finance software that covers
lending end to end
Onboarding with eligibility upfront
The borrower and the green project are onboarded together: one application captures financials,
asset specs, and eligibility proof, then runs KYC and KYB against it. The file is audit-ready
well before it reaches the credit team.
Origination across green products
Solar, EV, retrofit, and sustainability-linked loans all run on one configurable engine, each
with its own terms. AI scoring weighs borrowers that lack a long track record, while subsidies,
rebates, and KPI-based rate steps are built into the offer rather than bolted on after.
Servicing tied to KPIs
As the loan runs, repayments post, balances update, and the sustainability KPIs behind any rate
step are tracked against target. Where a margin ratchet applies, pricing moves with performance,
and impact data is ready for investor and framework reporting.
Collections that act early
Early-warning signals flag accounts that start to slip, so collections reach them before real
arrears build. Work is queued by exposure and days overdue, with automated outreach and a clear
path to restructure that brings money back and keeps defaults low across the green book.
Estimate your
green finance software in 3 minutes
STEP:
/
Online onboarding
From quote to funded green loan online
A borrower can price a loan, upload asset and eligibility documents, and e-sign without leaving the
browser. Identity and eligibility checks run quietly behind the scenes, so the team approves and
funds many more green loans with a lot less manual work.
Bring the borrower and the green asset onto the platform in a single application.
The system sizes the loan against the project and checks it against your eligibility
rules, so use-of-proceeds and exposure are clear before review.
Decide and fund online
No phone call is needed: the borrower links their data, attaches the asset
paperwork, and signs in the browser. HES LoanBox takes it from there, clearing KYC
and KYB, scoring the file, and returning a decision that can come back the same day.
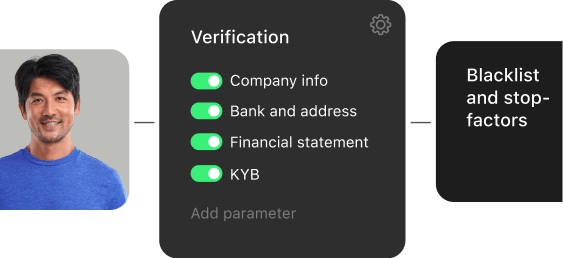
Eligibility and document checks
The borrower submits asset specs, supplier quotes, and any energy certificate. The
system checks them against the program eligibility criteria and flags missing or
inconsistent proof, so weak use-of-proceeds evidence shows up before you fund.
Grow through installer and dealer channels
Solar installers, EV dealers, and retrofit contractors get a portal of their own,
submitting borrowers at the point of sale and tracking approvals. Commission on
referred deals reconciles in the same place, so partner volume grows without new
branches.
Keep every green deal moving across the right teams
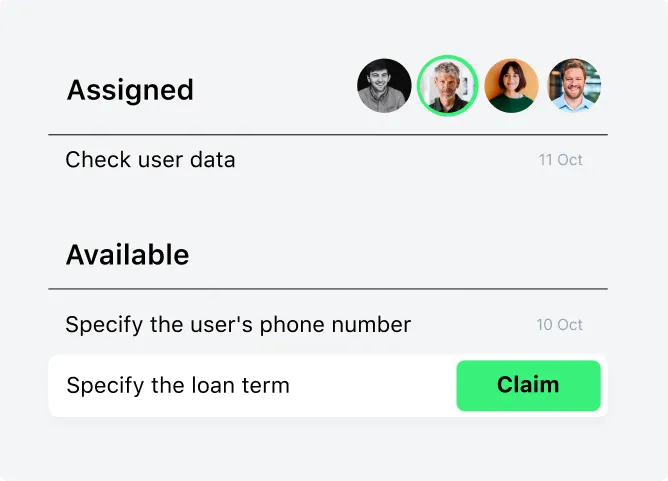
Nothing should sit idle while a borrower waits. Each application moves to the right reviewer by role
and current load, items drifting toward an SLA breach get flagged, and eligibility, credit, and
funding stay on one shared board.
Green origination
Confident green underwriting, even on thin files
Slow decisions cost green lenders deals at the installer counter and let weak files through. Every
application is verified and scored as it arrives, so each file returns a quick, well-grounded
answer.
The platform verifies the borrower and the green asset first, then fixes advance,
rate, and term from the project and your program rules. Pricing follows what the
asset can actually support, instead of a loan officer working the file by hand.
Your credit policy, applied your way
Set the policy once and HES LoanBox does the sorting: in-policy green loans clear on
their own, while anything outside the lines goes to a reviewer. You decide the
thresholds, by loan size, product, and risk band. The same lines apply to every
file.
AI scoring built for new green assets
Scoring can run on your existing scorecards, on the built-in AI engine, or on both
at once. Sound borrowers get approved faster, while thin or risky files are flagged
early, the pattern behind lenders cutting NPLs by up to 40%.
GiniMachine that learns from your book
Every funded green loan teaches the model something. GiniMachine watches how those
loans actually perform, adjusts its risk patterns by itself, then scores the next
application better than the last, no data scientist required. Accuracy climbs while
fewer loans go bad and fewer files need a manual look.
Green terms and staged disbursement
The green loan agreement, with its KPI and rate-step terms, is generated from a
template you control once approval is in. Money then goes out in stages as proof of
completed work comes in, and each milestone and document stays logged for later
review.
Green finance
lending software
with origination
automation
Application flow
Borrower profile
Decision-making
and much more
Green products you configure, not code
One HES LoanBox setup covers solar, EV, retrofit, green mortgage, and sustainability-linked
products at once. Rates, terms, and per-product eligibility are yours to set, and a new
green product can launch without waiting on engineering.
Loan agreements from set templates
Each green loan agreement comes out of a template already carrying rate, term, and any
KPI-linked conditions. Drafting errors drop, funding moves quicker, and the paper trail
stands up if a borrower or auditor wants to see how a deal was structured.
Subsidy and incentive handling
Rebates, tax credits, and grants fold into the offer instead of being tracked on the side.
Each incentive applies under its own program rules, and the platform keeps the math straight
so the borrower sees an accurate net cost.
Impact and KPI tracking
Sustainability KPIs and avoided-emissions figures are recorded against each loan as it runs.
Portfolio-level impact builds up in one place, ready to hand to investors or drop into a
framework report, without anyone rebuilding it in a spreadsheet.
Repayment reconciliation
Money coming in gets tied to the right loan and installment on its own, no one matching rows
by hand. The platform surfaces any shortfall, overpayment, or unapplied amount, which keeps
each balance correct without daily cleanup.
Workflows you change yourself
The path a green loan takes through eligibility, approval, and funding is edited in a visual
builder, not raised as an engineering ticket. Drop in a step, split the logic, and have it
live within days.
Workflows that match your green products
Loan servicing
Your green loan book, live in one place
When the core ledger only talks to spreadsheets, a slipping borrower stays invisible until the
default lands. A live book changes that: terms can shift as conditions do, and every repayment posts
straight to the loan it belongs to.
On its own, a loan carries from the first disbursement through to payoff, with no
spreadsheet in the loop. Your settings drive the repayment postings, fee charges,
KPI-based rate steps, and any term change, so servicing holds steady while the
portfolio scales.
Early warning on repayment risk
Risk surfaces on its own. A borrower who drifts late, trips a covenant, or misses a
sustainability target gets caught early, with enough runway left to restructure or
intervene before the loss is locked in.
Every loan and its impact in one view
In HES LoanBox, a borrower opens to one full picture: loan balance, repayment
history, the green asset financed, current KPI status, and today's risk position.
The loan and its impact sit side by side, not scattered across separate tools.
Moving repayments and disbursements
Money moves over ACH, direct debit, and bank transfer, whether it is a repayment, a
disbursement, or an incentive payout. The schedule is yours to set, balances update
as funds clear, and connected payment providers carry the load, so no one keys
transactions in by hand.
Get a 360-degree overview of your operations
Deal management
Product engine
Task management
Scoring
Reporting
Loan collections
Catch late green loans before they become write-offs
Every day a repayment sits unpaid, yield drains out of the green book. Queues the AI ranks, outreach
that fires on its own, and rules you control keep the team fast, inside policy, and bringing more of
what is owed back.
A missed or short repayment triggers the recovery flow you set up in HES LoanBox,
with no delay. The first message reaches the borrower that day, the account status
is rechecked, and the case escalates step by step according to how far behind the
borrower has fallen.
Chase the highest-recovery accounts first
Collections work best when it follows the largest expected return. Each overdue
account gets ranked by how much is likely recoverable, with a suggested channel and
timing, so finance also gets a realistic forecast for the month.
Reminders before the due date
Best of all is the payment that never goes late. Ahead of each due date, the
borrower gets a nudge by text, email, or phone, and the platform records which
reminders landed and which went unread.
Fees and adjustments, within policy
Ceilings come from your compliance policy, and late fees or adjustments never exceed
them. Penalty terms set up per product and region, the caps hold on every account,
and each charge and borrower contact is logged for audit.
Green lending reporting and analytics
Data flows into interactive dashboards that track your green book KPIs, from funded volume to
portfolio impact. Export what you need, and shape the metrics to your reporting.
Plug into 100+ integrations for green lending
Whatever a green lender already runs stays connected. An open API plus ready-made connectors wire
HES LoanBox to accounting and ERP, bank data and credit bureaus, identity and sanctions screening,
payment rails, e-signature, and reporting tools.
What comes with
our green lending software
Customization without limits
Modules adjust, workflows are yours to build, and approval routes follow whatever your
credit team signs off on. Connections span credit bureaus, bank data, and the accounting or
ERP stack you already run.
Pricing you can read
HES LoanBox pricing comes down to one license fee, with custom development only if you ask
for it. There is no per-seat charge, and users and borrowers stay unlimited. The developer
license puts the source in your hands, free of vendor lock-in.
3 to 4 month launch
Most green lenders are live in 3 to 4 months, lending sooner and reaching ROI long before a
legacy system would even be standing.
Expertise in lending
The analysts behind the platform have spent 10+ years in lending and credit across North
America, Europe, and emerging markets, and green finance is squarely in their wheelhouse.
Built by lenders, for lenders.
Certified security
ISO 27001 and SOC 2 certified, hosted on AWS or Google Cloud on a Java LTS stack, with
role-based access and full audit logs.
Support that responds
Whenever you need it, a dedicated team is there with fast, knowledgeable answers.
Success stories
HES FinTech has been our reliable technology partner since 2012. I believe much of our success is due to the well-architected HES LoanBox solution.
Role-based access, encryption both in transit and at rest, and a hardened
hosting environment keep borrower and applicant records protected. Every
deployment carries ISO 27001 and SOC 2 certification under a strict SDLC.
HES LoanBox can run on-premises, in a private cloud, or with a public
provider like AWS or Google Cloud. Pick whichever model your compliance
posture calls for, with no vendor lock-in.
Own the stack outright
Underneath: open-source technology with no licensing fees on top, plus Java
LTS, BPMN 2.0, Camunda, and Form.io. The HES LoanBox source code can be
yours outright, to adapt however you need over time.
Get future-ready, today
United States
United Kingdom
Europe
Germany
Japan
China
United States' Inflation Reduction Act (IRA)
America poured $369 billion into clean energy and carbon reduction. The package
offers substantial tax breaks for renewable projects, helps more Americans afford
electric cars, and funds both eco-friendly manufacturing and the green
infrastructure we need for a sustainable future.
Ministry for Energy Efficiency and Green Finance of the UK
With government support and financial backing, this institution is opening the door
to new lending opportunities in sustainability and energy efficiency—such as clean
heating, hydrogen, and carbon capture.
European
Green Deal
The initiative fuels sustainable progress through deep investments in clean energy,
green infrastructure, low-pollution transportation options, building renovation, and
circular economy solutions.
Germany's
Heating Act
The Act pushes to replace outdated gas and oil heating systems with greener, more
climate-friendly alternatives, as part of an ambitious goal to achieve climate
neutrality by 2045.
Japan's Green Growth Strategy
Backed by over $150 billion in government funding and subsidies, the initiative
encourages public-private collaboration, deregulation, and R&D support to foster
clean technologies.
China's Green Finance Initiative
With over 130 green finance policies already in place, China is creating an
ecosystem where financial institutions help drive the national carbon neutrality
goal by 2060.
Start green lending in 3 to 4 months
You grow the green book, HES FinTech runs the technology behind it.
Beyond the platform, HES FinTech brings hands-on lending and credit expertise to help you
shape green products that fit your market. The team works through your goals, configures HES
LoanBox around them, and stays available through launch with demos, onboarding, and ongoing
support, so you get more than software you have to figure out alone.
Can the green finance software be customized to our needs?
Yes. Products, workflows, forms, and approval routes are all configurable, so most of what
makes your lending distinct is configuration, not custom code. You can add integrations
through the open API, adjust eligibility and KPI rules, or build entirely new green
products. For anything deeper, the developer license lets your team extend the source
directly.
How secure is the green lending platform?
Security is built in and independently verified: HES LoanBox holds ISO 27001 and SOC 2
certification and follows a strict SDLC. Data is encrypted in transit and at rest, access is
role-based, and KYC, KYB, and sanctions screening run at onboarding. You can deploy
on-premises, in a private cloud, or with AWS or Google Cloud, whichever your compliance
posture calls for.
How long does it take to implement green lending software?
Most green lenders go live in about 3 to 4 months. The platform starts fast and mainly needs
configuring to your products and rules. If you need heavier customization or integrations
with legacy systems, it can take longer; in that case the team scopes the work and agrees
the timeline with you up front, so launch stays predictable.
Book a demo
HES FinTech has been our reliable technology partner since 2012. We owe much of
our success to their well-architectured solution.
Boris Batine, CEO at ID Finance
HES FinTech offers comprehensive front-to-back solutions with integrations. Our
machine learning platform will allow clients best-in-class investment advice.
Edward Downpatrick, Strategy Director at Fintuity
In just 6 months, we went from storing all our data in Excel to a fast,
reliable, and user-friendly platform that caters to our specific needs.
Hjortur H. Jonsson, Partner at ALM Securities
HES developed our lending software and predictive analytics. Their expertise
delivered automation, clear UI/UX, and customer portal.
Mazen Alasnag, Head of Loan Management at Wa’ed
The LMS provided flexible repayment options, automated restructuring and
branch-level management, enhancing efficiency and risk mitigation.