Built for banks, financing and lending companies, digital banks, and cooperatives. One platform for CIC
credit data, transparent pricing, and servicing across the cycle.
Every peso of processing cost matters when tickets are small and volume is high. Automate
the manual steps across a loan to protect margin without loosening borrower checks.
60%
cost reduction
Thin or missing credit files mean a CIC pull rarely tells the full story. Score on
behavioral and alternative data to approve good borrowers others reject.
3x
scoring accuracy
Disclosure forms, KYC files, collection follow-ups. Pull the repetitive data entry out of
these tasks so staff spend their time on decisions, not paperwork.
44%
staff efficiency
Loan management system
for the whole lending cycle
SEC-ready onboarding
One borrower journey covers salary loans, microfinance, and BNPL. Applicants enter their details
once, identity and screening checks run inside the flow, and weak files get flagged before a
credit officer opens them.
Learn more
Configurable origination
Pull credit and affordability data from CIC, CIBI, and TransUnion in a single screening step.
Set pricing, rules, and disclosure documents per product, whether personal, auto, or BNPL, and
clone that setup for whatever you launch next.
Learn more
Full-cycle servicing
Repayments post from InstaPay, PESONet, and auto-debit straight onto a live ledger.
Restructures, payment holidays, and re-pricing happen in the system, not in Excel, and every
action lands in a record you can audit later.
Learn more
Compliant collection
Run arrears within fair-collection limits. Cases sort by delinquency stage, outreach goes out
over SMS, voice, and e-wallet reminders, and AI sets the recovery approach that fits each
struggling borrower.
Learn more
Get your lending
product estimate
in 3 minutes
STEP:
/
Digital onboarding
Digital onboarding that fits Philippine lending
Long forms and unclear pricing are where applicants give up. HES LoanBox walks them from the opening
tap to a signed agreement, collects only what your underwriters actually need, and keeps a clean
record of every step, so no one retypes the same data across three systems.
Applicants see the amount, term, and monthly repayment against the effective
interest rate, computed live as they go. Showing real numbers this early holds
people in the flow and meets the Truth in Lending disclosure, so nothing jumps out
at them after approval.
Keep borrowers close after payout
A self-service portal lets borrowers track the schedule, view their balance, move a
due date, or flag a problem without phoning the office. SMS and email nudges bring
down missed payments, and the log records what everyone did.
Grow through agents and partners
Agents and partner channels get their own branded portal to send in deals and follow
each decision as it moves. One dashboard shows submission volume, channel split, and
approval rates, and there is no second system to set up for them.
Loan origination
AI and automation
for faster loan origination
When data is rekeyed by hand and bureau files are weeks old, a simple decision drags on. Pull live
bank and e-wallet feeds, read payslips and IDs with OCR, and sign in the app, and each file becomes
a quick, defensible yes or no, with document handling down by as much as 90%.
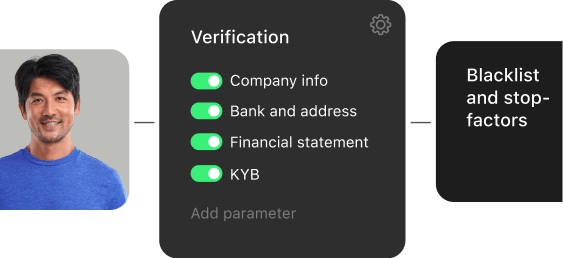
Confirm who the applicant is, check sanctions lists, and clear a biometric match in
seconds. The file then pulls credit data from CIC, CIBI, or TransUnion, a PhilSys
check, and bank or e-wallet history when the borrower works for themselves.
Underwriting that follows your risk policy
Approvals land as much as 80% quicker on a rules engine set to your own credit
policy. Route each case automatically, in a hybrid mode, or by hand, split by risk
band, amount, or product, giving up neither conversion nor compliance.
Approve more of the good risk
Write your own scorecards rule by rule and refine them as the portfolio grows. Or
switch on
GiniMachine,
HES LoanBox's built-in AI scoring engine, which retrains on each funded loan and
lifts accuracy as much as 3x past bureau-only models. Both paths cut NPLs by up to
40%.
And other loan origination features
Unlimited product range
A single core handles your whole catalog, personal and salary loans, auto, BNPL, and the
rest. Set pricing, fees, repayment schedules, and eligibility in configuration, not in a
developer's backlog.
Customizable application flow
Design the borrower journey without code, on a drag-and-drop builder. Map out where
approvals happen and how cases route, then ship a new product in days when the rules move.
Roles-based access
Borrower data stays behind role permissions, password policies, per-device limits, and
two-factor sign-in. Every action a user takes lands in an audit trail you can hand to a
reviewer.
Agreements in seconds
Generate enforceable loan agreements in seconds from dynamic templates. Disclosure
statements, the contract itself, and the repayment schedule come out together, worded to
what Philippine lending rules expect.
Configurable lending workflows for Philippine lenders
Loan servicing
Complete loan management system for Philippine lenders
Run servicing on spreadsheets and a couple of loosely wired tools and you quietly bleed margin, and
borrower trust with it. HES LoanBox holds a loan's entire lifecycle on one set of live data, with
terms you configure and payments built in, which keeps the work clean and review-ready.
Carry a loan from release to closing on workflows you control. Interest accrual,
penalty charges, restructures, refinances, and payoff figures all follow your rules,
and one record keeps each borrower's applications, open loans, and complaints
together.
Adjust terms on the fly
Few loans run exactly the way they were signed. Build the adjustments borrowers
actually ask for, payment holidays, longer terms, rate changes, partial settlements,
or a full restructure, and your team applies any of them in minutes while the log
keeps every change.
Payments on Philippine rails
Wire up InstaPay, PESONet, auto-debit, e-wallets, and card rails through ready
provider connectors. Push disbursements on schedule, reconcile incoming repayments
automatically, and card details stay inside the PCI boundary your acquirer
maintains.
A healthier loan book
through AI risk scoring
Explainable scoring for examiners
Score every stage of the loan, from the first applicant screen through to NPL forecasting.
The reason codes behind each result stay clear enough for your credit committee, or an
examiner, to read.
AI accuracy at scale
Learning from your own portfolio, the AI lifts accuracy up to 3x beyond bureau-only scores,
working from live transaction behavior instead of a credit file pulled months ago.
Risk-based pricing controls
Set thresholds segment by segment, spot repayment strain before it turns into arrears, and
adjust pricing as a borrower's cashflow changes.
Debt collection
AI debt collection software
for the Philippines
In the Philippines, rules on fair collection and strict data-privacy duties turn recovery into a
compliance question, not only a cash one. HES LoanBox runs each account through workflows shaped by
affordability, respectful contact, and the fee ceilings you operate under.
Take the repeat chasing off your collectors and keep overdue cases flowing.
Contact borrowers over SMS, voice, email, an auto-dialler, and Viber
Route each case by delinquency stage and product on a ready-made or custom
workflow
AI-tuned strategy for each case
Drop one-size dunning for a recovery plan built from how each borrower behaves.
Choose the outreach sequence that earns the most responses
Hand AI the timing, tone, channel, and exact wording
Order the book so the accounts most likely to pay surface first
Forecast collections and the write-off you are exposed to before the next
reporting cycle
Fees and interest within the limits you set
Apply penalty interest and any fees only within the ceilings that govern your
products.
Configure fee and interest rules per product
Keep borrower messaging plain and a trail ready for any review
Lending reporting and analytics
HES LoanBox puts the metrics your CFO, controller, and credit committee follow onto live dashboards.
Export the raw data regulators ask for, build your own metrics, and slice the portfolio by vintage,
by channel, or by product.
100+ integrations for your Philippine lending stack
HES LoanBox plugs into the stack you already run, with prebuilt connectors for CIC, CIBI, and
TransUnion, the InstaPay and PESONet rails, and your accounting, core-banking, and KYC tools.
Why Philippine lenders
choose HES LoanBox
Unlimited customization
Reshape modules, redesign how borrowers move through it, and hook in any local service, from
CIC to the payment rails. You own the source code, with no vendor lock-in.
Transparent pricing
You pay for the license; a custom build is the only add-on. Borrowers, agents, and internal
users are all unlimited, with no per-seat fee as the book grows.
3-month launch
A standard build goes live in about 3 months. You lend sooner, hit ROI earlier, and keep
refining the platform as volumes climb.
Philippine lending expertise
Work with the analysts and engineers behind a decade-plus of lending products built for
banks, non-bank lenders, and fintechs.
Bank-grade security
ISO 27001 certified, SOC 2 aligned. Run on AWS, Google Cloud, on-premises, or hybrid, on a
secure Java LTS stack with regular updates.
Dedicated support
Reach a support team that understands lending and keeps your business hours.
ISO 27001 certification, SOC 2 alignment, and SDLC hold security tight
across every operation, with full data encryption, role-based access, audit
trails ready for review, and a hardened hosting setup.
HES LoanBox deploys on AWS, Google Cloud, on-premises, or in a hybrid setup,
matching your IT estate and your board's data preferences.
Open-source backend stack
HES LoanBox runs on free and open-source foundations like Java LTS, BPMN
2.0, Camunda, and Form.io modeler. The stack keeps licensing fees off the
table apart from the platform source code, so your team knows what it owns.
The 2026 reality of
Philippine lending
50%
account ownership in 2024
The World Bank 2025 Findex put
account ownership
at 50.2% of Filipino adults, below the lower-middle-income average. Alternative-data scoring
reaches the thin-file borrowers a bureau pull alone misses.
57%
of retail payments digital
The BSP reported
57.4% of retail transactions
went cashless in 2024, past its own target. Disbursing and collecting over InstaPay and
PESONet keeps servicing on the rails borrowers already use.
Jun ’26
AFASA auth deadline
Under BSP
Circular 1213, supervised lenders must drop SMS and email OTPs for high-risk actions by 30 June 2026 in
favor of stronger methods. Step-up identity and device checks are built in, with every step
logged.
76%
of 2025 fraud losses
Social engineering, account takeover, and identity theft drove
76% of fraud losses
the BSP tracked in 2025. Layered identity, device, and KYC verification stops more before
money moves.
Go live in 3-4 months
You build the book; HES LoanBox carries everything underneath.
How can HES LoanBox benefit my lending business in the Philippines?
For Philippine lenders, HES LoanBox is one secure, fully digital platform, automated end to
end. It moves more volume, makes fewer errors, stays aligned with local regulators, and
ships solid reporting and workflow tools. You get quicker processing, an easier borrower
experience, and stronger margins.
Can HES LoanBox integrate with our existing systems?
Yes. Through its APIs, HES LoanBox plugs into the systems you run today, your KYC and eKYC
providers, the local credit bureaus, the InstaPay and PESONet rails, and the rest of your
financial tooling, so data moves cleanly end to end.
How long does implementation take?
A typical deployment in the Philippines runs about 3 to 4 months, set by how involved your
requirements and existing systems are. The platform is built to stand up fast, and our
people sit alongside yours from kickoff through go-live. More complex builds take longer,
which is expected.
What security measures protect data?
HES LoanBox applies strong protection: encryption, secure storage, and regular audits. It is
ISO 27001 certified and SOC 2 aligned, and supports compliance with the Data Privacy Act and
the rules the National Privacy Commission enforces, so borrower data stays guarded at every
step.
What makes the software fit the Philippine market?
It is shaped to how lending works here. HES LoanBox pulls credit data from CIC, CIBI, and
TransUnion, runs affordability and Truth in Lending disclosure, and settles payments over
InstaPay, PESONet, and e-wallets. We fit the workflows and integrations to your license
terms and your chosen providers, whether you answer to the SEC or the BSP.
Which types of Philippine lending does HES LoanBox support?
Most Philippine lending models are a fit. Personal and salary loans, microfinance, SME,
auto, BNPL, point-of-sale, or online lending, the platform supports them. Because it is
modular, we shape the workflows, the risk rules, and the compliance logic to your kind of
lending, or build a solution from scratch when your model needs it.
Does HES LoanBox help with SEC and BSP compliance?
Yes. Whether you run as an SEC-licensed lending or financing company or a BSP-supervised
bank, HES LoanBox supports the disclosure, recordkeeping, and audit trails local rules
expect, and the stronger authentication AFASA requires by mid-2026. We configure the
workflows to your license and reporting obligations.
Book a demo
HES FinTech has been our reliable technology partner since 2012. We owe much of
our success to their well-architectured solution.
Boris Batine, CEO at ID Finance
HES FinTech offers comprehensive front-to-back solutions with integrations. Our
machine learning platform will allow clients best-in-class investment advice.
Edward Downpatrick, Strategy Director at Fintuity
In just 6 months, we went from storing all our data in Excel to a fast,
reliable, and user-friendly platform that caters to our specific needs.
Hjortur H. Jonsson, Partner at ALM Securities
HES developed our lending software and predictive analytics. Their expertise
delivered automation, clear UI/UX, and customer portal.
Mazen Alasnag, Head of Loan Management at Wa’ed
The LMS provided flexible repayment options, automated restructuring and
branch-level management, enhancing efficiency and risk mitigation.