For fintech lenders, banks, and retail finance companies. One platform to approve shoppers in seconds,
onboard merchant partners in hours, and manage the full installment lifecycle end to end.
Approve shoppers in seconds with automated affordability checks and real-time decisioning
that fit naturally into the pace of the checkout journey.
90%
quicker credit decisions
Process high application volumes across merchants, channels, and peak retail periods without
adding operational strain or slowing the borrower experience.
10x
capacity
Segment installment borrowers by repayment behavior, identify accounts worth proactive
outreach, and improve collections without damaging customer loyalty.
25%
improved recoveries
Full-lifecycle point-of-sale finance software
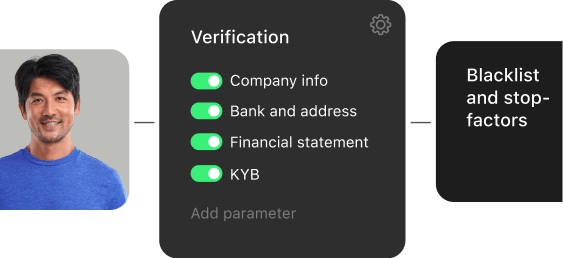
Fast merchant onboarding
Launch a co-branded checkout widget that runs on any device or sales channel.
Give retail partners a fast, fully digital path to activation,
with KYC, document intake, and merchant account setup completed automatically from day one.
Origination built for the checkout moment
Run instant credit decisions against your own risk rules, AI scoring, and live Open Banking
affordability signals.
Configure
each installment product with its own eligibility thresholds, promotional rate logic, and
pricing tiers, covering every retail vertical you operate in.
Clean servicing across every merchant account
Track disbursements to merchants, installment schedules, and customer communications from a
single back-office view.
Automate
the full post-origination lifecycle and keep settlement data current across every retail partner
and channel.
Collections that protect merchant relationships
Improve collection rates on late installment accounts through AI-powered outreach, delinquency
prediction, and repayment plan adjustments that keep borrowers on track without damaging the
merchant relationships your book depends on.
Task management for point-of-sale lending teams
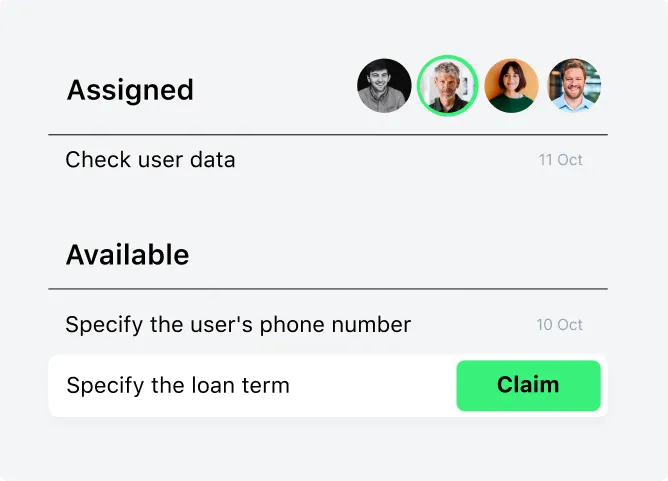
Move every installment application and merchant request forward without delays. Auto-assign tasks by
role and workload, track SLAs in real time, and keep origination, verification, and servicing teams
fully in step.
Online onboarding
POS lending software: checkout financing platform for retail lenders
Convert more shoppers at the moment of intent. Give customers a fast, fully embedded route to
installment finance right at checkout — so your origination team processes more applications across
more merchants with the same headcount.
Show installment options before the shopper hesitates
An embedded checkout calculator lets shoppers adjust installment amounts, payment
frequency, and term length in real time. Seeing the monthly cost before they apply
removes the main reason customers abandon a financed purchase mid-flow.
Approve at the till, not the next day
Shoppers confirm their details, pass document checks, and countersign the
installment agreement at the till. Decisioning runs automatically, bringing the gap
between application and funds release from hours down to seconds.
Keep buyers on track after the purchase
A white-label portal gives installment buyers a live view of their payment schedule,
next due date, and remaining balance. Timely SMS and push alerts cut late
installments and maintain borrower engagement throughout the repayment term without
manual outreach from your servicing team.
Expand your retail network without expanding your team
Give each merchant its own portal for submitting finance applications, checking
approval status, and reviewing customer accounts. Bring new retail verticals and
sales channels onto your POS lending platform without adding internal support
capacity or onboarding overhead.
Get your lending
product estimate in 3 minutes
STEP:
/
POS loan origination
Cut installment origination time
at the point of sale
with AI and
automation
A slow decision at checkout costs the sale for good. HES LoanBox automated checks and underwriting
rules give every installment application a decisive answer before the shopper has time to
reconsider.
Most retail installment applicants have no prior finance history with you. Pull in
bureau scores, Open Banking income signals, and supplementary data sources
automatically — so your POS loan origination engine works from a complete picture on
the very first transaction, not a partial one.
Different merchants, different risk rules — one engine
Electronics, furniture, healthcare, home improvement — each vertical carries its own
risk profile and average basket. Configure separate decisioning rules per merchant
category, run them fully automated or with manual review, and adjust the logic
without a development sprint when conditions change.
The approvals your competitors are missing
Most POS lenders leave margin on the table through overcautious decisioning.
Activate the embedded AI engine alongside your own policy rules to identify
creditworthy buyers that static models turn away, bring NPL rates down by up to 40%,
and grow the portfolio without adding disproportionate risk.
Self-learning scoring by GiniMachine
GiniMachine's scoring model gets sharper with every installment decision on your
retail book. It tracks repayment outcomes, detects new risk patterns across merchant
verticals, and refines its predictions continuously — raising approval accuracy and
cutting defaults without extra analyst time.
Paper at the checkout kills conversions
Every second a shopper spends on paperwork is a second they reconsider the purchase.
OCR validates IDs and income proof instantly, embedded eSignature closes the
agreement at the till on any screen, and processing costs fall by up to 90% —
without a single printed form.
and much more
Unlimited installment product configuration
HES LoanBox retail credit software lets you launch any installment product your retail
partners need — installment plans, buy now pay later programs, or deferred purchase options.
Configure rates, fees, repayment terms, and eligibility criteria per product, merchant
category, or seasonal campaign without a developer.
Automated contract generation
Generate signed installment agreements in seconds from merchant-specific templates with
automatic data population. Remove manual drafting, cut the time between approval and
disbursement, and keep documentation current with consumer credit standards in every market
you operate.
Smart notification templates
Build SMS, email, and push alert templates with variable fields for every buyer touchpoint —
approval confirmation, payment reminders, missed installment follow-ups, and renewal offers
for your best payers.
Role-based security and access control
Separate access levels for merchant portals, borrower accounts, and operations teams.
Granular permissions, two-factor authentication, and device-level controls keep data
protected, with a full activity log behind every action.
Multichannel buyer communication
Send payment reminders, overdue notices, and account updates through SMS, email, and in-app
alerts triggered automatically by repayment events and borrower behavior. Keep installment
buyers engaged without adding manual workload to your operations team.
No-code workflow builder
Build and adjust POS lending workflows without code. Configure approval steps, merchant
onboarding sequences, and application flows, then roll out changes within days when you add
a product or a new retail vertical.
Configurable point-of-sale lending workflows
POS loan servicing
Installment lending software that covers every point-of-sale channel
Installment books spread across dozens of merchant partners are impossible to run on spreadsheets.
HES LoanBox handles the complete servicing lifecycle with real-time settlement data, flexible
repayment terms, and built-in payment processing covering every retail channel you operate.
Run every retail installment from merchant disbursement to final repayment without
manual steps. Interest accruals, fee calculations, early repayments, and refinancing
all execute against your business rules, eliminating reconciliation work at the end
of every period.
Full installment portfolio control
Manage installment plans, promotional credit accounts, and revolving retail lines in
one back-office view. Adjust schedules, apply payment deferrals, process partial
payments, and restructure balances instantly, with a clean audit trail behind every
change.
360° buyer and merchant view
Pull up any buyer's full installment history, active accounts, documents, and
repayment status at a glance. See which merchants generated each account, spot
refinance or top-up opportunities, and equip your servicing team with the context to
close queries on the first call.
Merchant settlement and payment processing
Disburse funds to merchants and collect buyer repayments through pre-integrated card
networks, ACH, SEPA, and regional payment rails. Settlement runs on schedule,
ledgers stay current without manual posting, and PCI DSS controls are built in from
day one.
Maximize retail installment portfolio performance
with AI risk intelligence
Scoring your team can explain
Score every installment applicant from first screen to NPL risk, with transparent
underwriting outputs your underwriters can justify to merchants, regulators, and credit
review teams.
Three times the decisioning accuracy
Integrated AI delivers up to 3x better precision than static rule-based models, approving
more retail installment buyers without increasing portfolio risk or adding manual review
overhead.
Risk thresholds that move with your merchants
Set risk parameters per merchant vertical, surface early delinquency signals before they
become defaults, and adjust installment pricing dynamically to keep margins intact through
seasonal demand shifts.
POS installment collections
Recover more without
damaging the merchant relationship
Aggressive recovery tactics that work for unsecured lending can kill a retail partnership overnight.
HES LoanBox automates outreach, scoring, and penalty management with tools that protect installment
repayment rates and your retail network at the same time.
When an installment goes overdue, the recovery sequence starts automatically.
Outreach runs across the right channels, collection documents are generated and
filed without manual steps, and each account moves through a workflow matched to its
delinquency stage and borrower segment.
AI that targets the right borrower first
Not every late account needs the same attention. The AI engine scores each
delinquent installment by recovery probability, separates high-yield accounts from
restructure candidates, and helps your collections team spend time where it actually
moves the dial.
Intervene before an installment goes overdue
The cheapest recovery is the one you never need. Personalized reminders go out days
before each payment falls due, through whichever channel the buyer responds to best
— SMS, email, push, or voice — giving them every reason to pay on time.
Fee and penalty rules that stay within limits
Late fees apply correctly on every overdue account without manual calculation. Rules
are configured by product type, merchant category, and market, compliance caps
trigger automatically, and every communication is stored so nothing is missing when
an audit or dispute lands.
100+ integrations to connect your point-of-sale lending stack
HES LoanBox plugs into the infrastructure your POS lending platform already runs on — credit
bureaus, KYC providers, Open Banking services, payment gateways, checkout platforms, and
communication services — through pre-built connectors and an open API.
Point-of-sale installment reporting and analytics
HES LoanBox gives your team a live view of installment portfolio performance by merchant, product
line, and retail vertical. Configure the metrics that matter, pull custom reports on demand, and
track the numbers that drive pricing and risk decisions across your POS lending operation.
Security
Deployment
Tech stack
Enterprise-grade security
ISO 27001 certification and SDLC controls keep every operation secure,
backed by full data encryption, granular access management, and hardened
hosting infrastructure.
HES FinTech point-of-sale lending software runs on-premises or in the cloud
— AWS, Google Cloud, or any provider your team already uses.
Powerful backend tools
HES FinTech builds on free and open-source foundations: Java LTS, BPMN 2.0,
Camunda, and Form.io modeler. No extra licensing fees apply beyond the
platform's own source code.
The 2026 reality of
point-of-sale finance
70%
of online shopping carts are abandoned before purchase
Seven in ten shoppers who add an item to a cart leave without buying. Installment finance at
checkout reduces that hesitation directly, at the moment purchase intent is highest. (Baymard Institute, 2026)
10x
growth in US BNPL originations between 2019 and 2021
The US BNPL market grew nearly tenfold in two years, reaching $24.2 billion in originations
in 2021. Installment finance at the point of sale has moved from a niche option to a
standard buyer expectation. (CFPB, September 2022)
$45.2bn
BNPL originations in 2023 from the six largest US providers
In 2023 alone, the six largest BNPL providers originated 335.8 million loans totalling $45.2
billion — continuing to grow at 23% year-on-year even after the explosive early expansion
had slowed. (CFPB, December 2025)
53.6m
active BNPL users in the US in 2023, up 12% year-on-year
53.6 million US consumers used BNPL in 2023, each taking an average of 6.3 loans per lender.
The volume is there. The question is whether your platform can originate, service, and
collect at that pace. (CFPB, December 2025)
Start lending in just 3 months
Focus on scaling your POS lending platform. HES FinTech takes care of the rest.
Point-of-sale lending software is the purpose-built infrastructure lenders, banks, and
retail finance companies use to offer installment credit at the moment of purchase —
in-store, online, or through embedded checkout flows. It spans the full lifecycle: merchant
onboarding, buyer identity and affordability checks, real-time credit decisioning,
installment agreement generation, repayment servicing, and collections. The category covers
dedicated POS lending software, installment lending software for multi-merchant operations,
and broader retail credit software handling everything from thin-file decisioning to
merchant settlement. HES LoanBox serves organizations that need one configurable platform
across their full POS lending book, rather than five disconnected tools.
How is POS lending software different from a standard loan origination system?
A standard LOS covers intake, decisioning, and closing — the front half of a credit
application. POS lending software extends further: embedded application flows inside a
merchant checkout, credit scoring that returns an answer in seconds, merchant portal
management, installment product configuration, and post-origination servicing. Standard
origination platforms handle volume but rarely touch the merchant network, promotional
product engine, or settlement layer. A dedicated POS loan origination platform — HES LoanBox
being a strong example — unifies origination, servicing, collections, and merchant
management in one environment, which matters when your book spans dozens of retail partners
across multiple verticals.
What installment products can I configure in HES LoanBox?
HES LoanBox retail credit software supports the full range of point-of-sale installment
products without requiring separate systems per product type. You can configure standard
installment plans with fixed monthly repayments, 0% promotional credit for merchant-funded
campaigns, deferred purchase programs where repayment starts after a defined period,
revolving retail credit lines with variable drawdown, and buy now pay later structures with
short-term split payments. Each product carries its own eligibility rules, rate logic, fee
structure, and term range. Product parameters can differ by merchant vertical, campaign, or
borrower segment, and changes deploy without a development sprint.
How does credit decisioning work in POS lending software at the checkout?
In checkout financing software, the decisioning window is measured in seconds. When a buyer
initiates a financed purchase, HES LoanBox simultaneously runs identity verification, KYC
checks, bureau scoring, along with Open Banking affordability signals, then applies your
configured underwriting rules to return an approve, decline, or refer outcome before the
shopper reconsiders. The complete POS credit decisioning flow — from submission to signed
installment agreement — finishes in less than a minute from a phone, tablet, or desktop
screen. You control the logic per merchant vertical and risk band, and can layer AI scoring
alongside rules-based models to lift approvals without adding portfolio risk.
Can POS lending software handle multiple merchant partners at scale?
Managing a multi-merchant POS lending platform takes more than a shared origination engine.
HES LoanBox gives each retail partner its own merchant portal for submitting applications,
tracking approval status, and reviewing their customer book. Merchant onboarding is fully
digital — KYC, document intake, and account setup complete automatically from day one.
Configure separate underwriting rules, installment products, and settlement terms per
merchant or vertical. New partners join without adding internal support overhead. With ten
merchant partners or a thousand, the same POS lending software handles origination volume,
settlement, and collections across the whole network.
How long does it take to implement a POS lending platform?
Most HES LoanBox deployments go live within three months — a timeline driven by modular
architecture and a pre-built connector library. The standard rollout covers POS loan
origination setup, merchant portal configuration, installment product build, payment rail
connection, and team onboarding. Deployments with deep core banking integration or bespoke
workflows take longer; that holds for any serious lending platform. HES accelerates delivery
through a no-code builder that lets your team set up application flows and decisioning logic
independently, backed by 14 years of POS and installment lending deployments across 160+
businesses in 32 countries.
What integrations does point-of-sale finance software need to support?
A complete point-of-sale finance software stack connects across six categories. Credit and
identity: bureau providers, KYC platforms, Open Banking affordability services. Payments:
card networks, ACH, SEPA, and local payment methods covering merchant disbursement and buyer
repayment. Checkout: embedded widgets, eCommerce platforms, and in-store terminal
connections. Communication: SMS gateways, email, and push notification services. Analytics:
BI tools and data warehouse connectors. Core banking: ledger posting and GL reconciliation.
HES LoanBox ships with 100+ pre-built connectors spanning all six categories, plus an open
API for any provider not yet in the library.
How does HES LoanBox handle compliance and data security for POS lenders?
HES LoanBox meets the security and compliance standards regulated POS lenders require. The
platform holds ISO 27001 certification, encrypts all data at rest and in transit, enforces
role-based access across merchant portals and back-office teams, and logs every user action
for a full audit trail. Payment processing operates on PCI DSS-compliant infrastructure. For
regulatory compliance, configurable penalty caps, consumer credit disclosure workflows, and
complete documentation trails keep every installment account examination-ready under
applicable consumer credit regulation — with no manual reconstruction needed when an audit,
dispute, or reporting obligation arrives.
Book a demo
HES FinTech has been our reliable technology partner since 2012. We owe much of
our success to their well-architectured solution.
Boris Batine, CEO at ID Finance
HES FinTech offers comprehensive front-to-back solutions with integrations. Our
machine learning platform will allow clients best-in-class investment advice.
Edward Downpatrick, Strategy Director at Fintuity
In just 6 months, we went from storing all our data in Excel to a fast,
reliable, and user-friendly platform that caters to our specific needs.
Hjortur H. Jonsson, Partner at ALM Securities
HES developed our lending software and predictive analytics. Their expertise
delivered automation, clear UI/UX, and customer portal.
Mazen Alasnag, Head of Loan Management at Wa’ed
The LMS provided flexible repayment options, automated restructuring and
branch-level management, enhancing efficiency and risk mitigation.