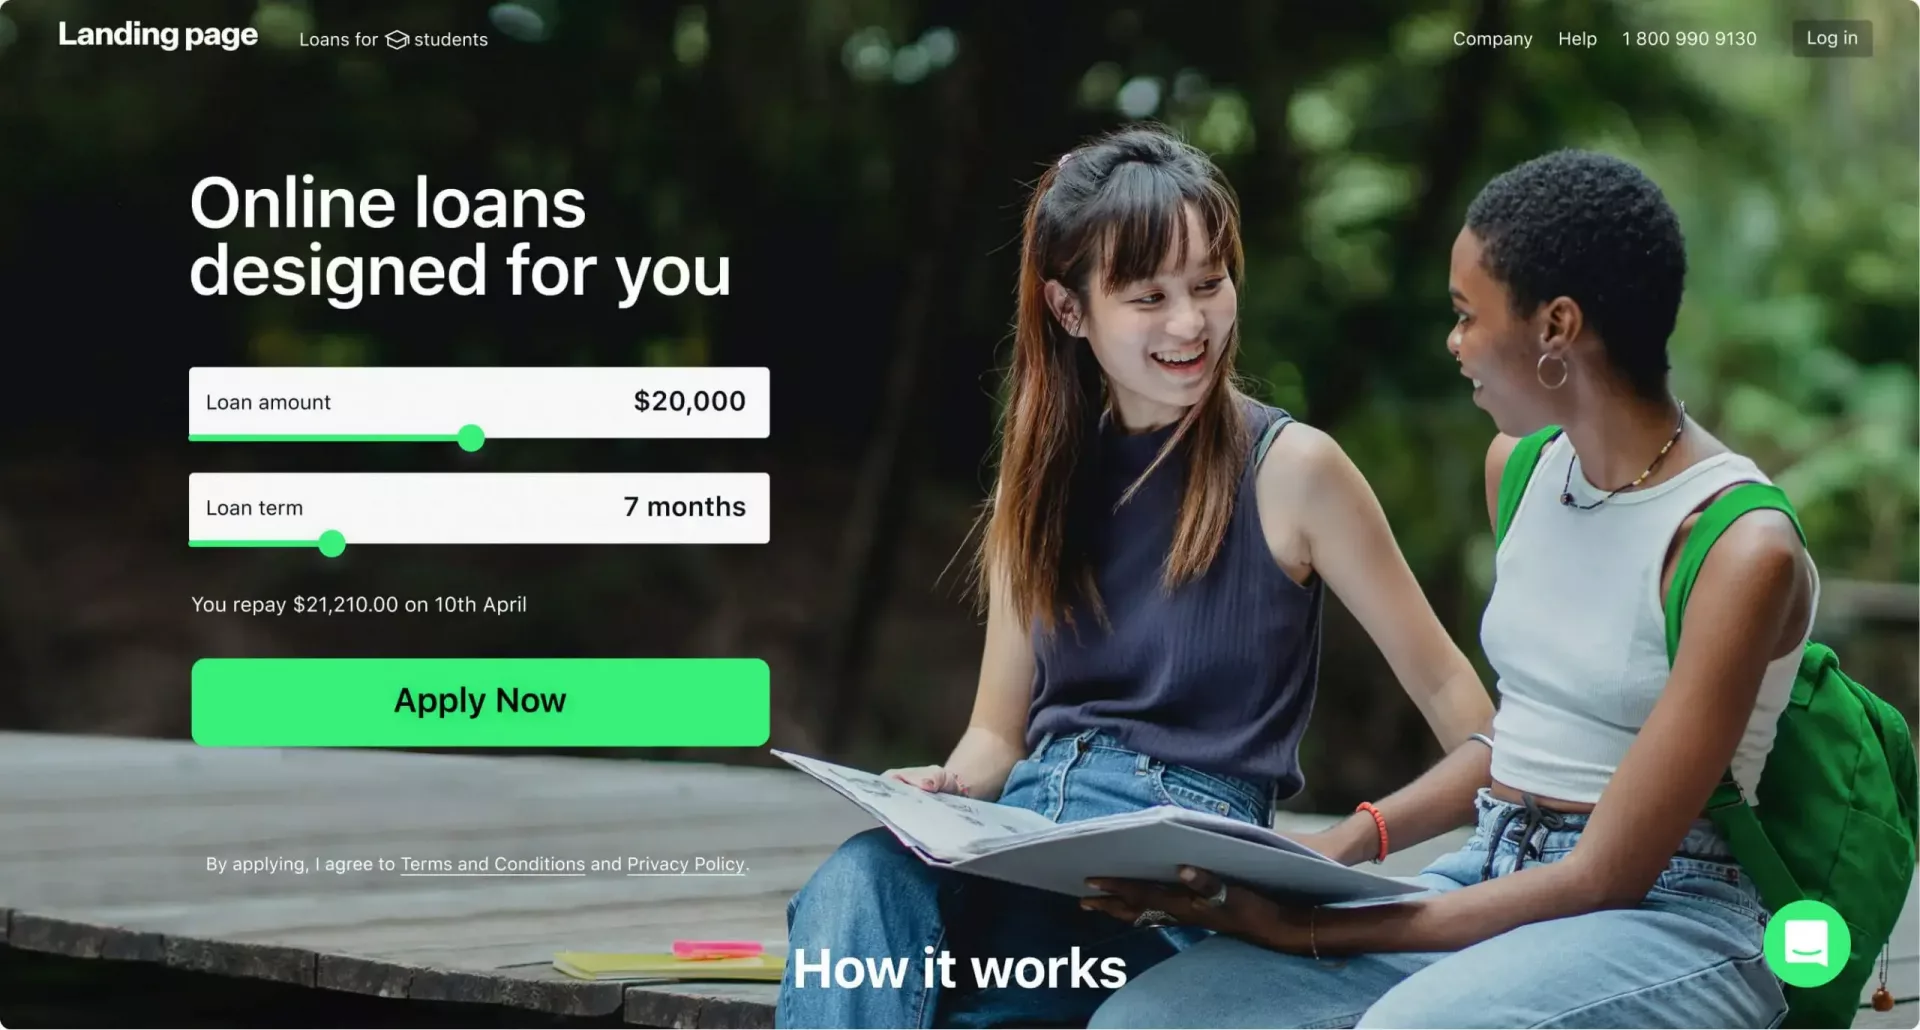
Small businesses are increasingly turning to online fintech lenders for financing. Data from the Federal Reserve's Small Business Credit Survey marks the shift: the share of US small business financing applicants seeking funds from online fintech lenders rose from 17% in 2020 to 29% in 2025.
Borrower relationships involve far more than initial loan origination. After funding, lenders still need to manage repayment schedules, payment processing, document collection, account updates, and ongoing communications. Bringing these activities into a single platform reduces manual work and gives borrowers one place to manage their loans.
In this article, we’ll break down what white-label lending platforms are, explore their main benefits, walk you through the key aspects to evaluate before choosing one, and share examples of standout solutions on the market.
What is a White Label Lending Platform?
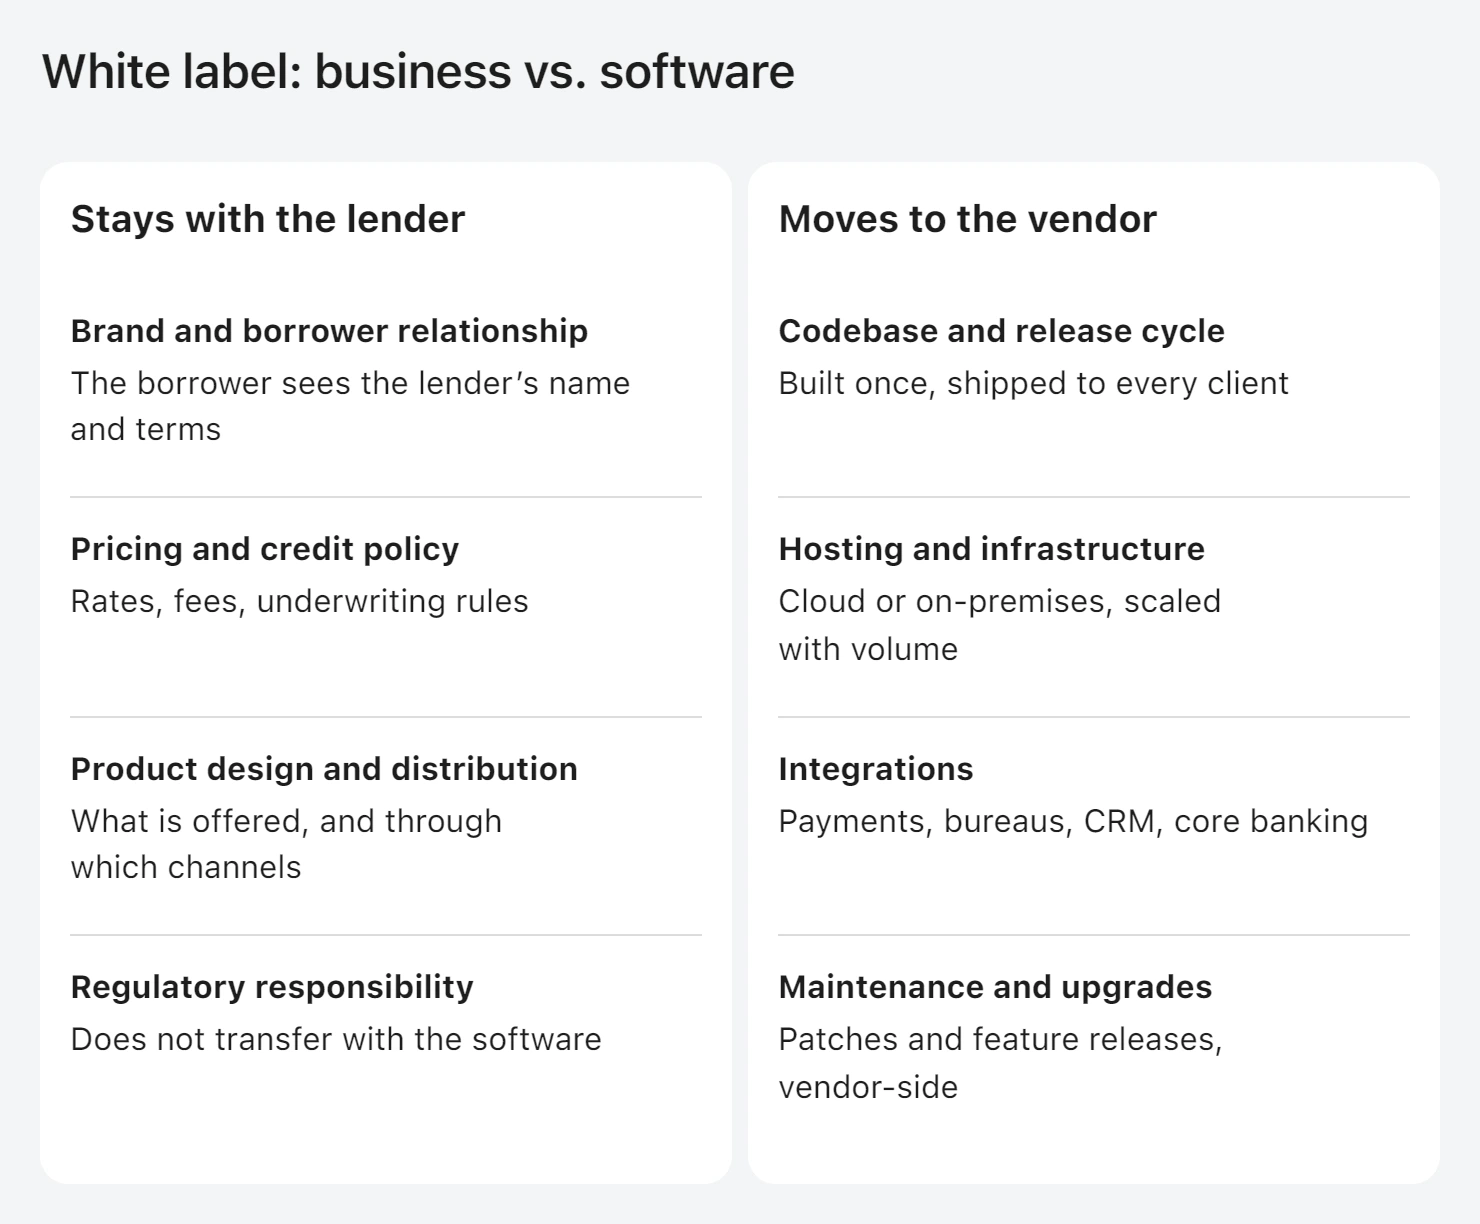
A white label lending platform is software built and operated by a technology vendor, then presented to borrowers under the lender's own brand and terms. The credit relationship, the pricing, and the underwriting policy stay with the business that licenses it, while the codebase, the hosting, and the release cycle remain with the provider.
Coverage typically spans the full cycle, with loan origination and credit scoring at the front end, white label loan servicing and collections at the back, and reporting across both.
Under that split, the licensee concentrates on product design, distribution, and credit policy, while the vendor maintains integrations and carries the platform through volume growth. Regulatory responsibility does not transfer with the software, as the licensing section below sets out.
White Label Lending Platform: How It Works
Companies entering the market generally choose between building a custom platform from the ground up and buying a ready-made solution, weighing control against speed and cost efficiency.
A custom platform gives the widest architectural control, letting lenders tailor complex workflows and security protocols to their own specifications. The cost is a significant capital expenditure and a development cycle measured in years, followed by in-house engineering support for scaling and maintenance afterward.
A white label lending platform is the middle route. It combines pre-configured infrastructure behind a customizable client interface. This significantly reduces initial setup costs and accelerates return on investment compared to in-house development.
This article compares the different delivery models, breaks down what white-label lending platforms are, explores their main benefits and the key aspects to evaluate, and reviews five solutions on the market.
White Label Embedded Lending, LaaS, and BaaS: How the Models Differ and Combine
A company's choice of model stems from the technology and licensing it already possesses.
Embedded lending, a segment of the wider embedded finance market, describes where the credit offer appears in the customer journey, and lending-as-a-service (LaaS) defines how the technology behind it is delivered.
White-label lending identifies whose brand the borrower sees, while banking-as-a-service (BaaS) defines who holds the regulatory license and underlying accounts. A private-label or co-branded program specifies whose name appears directly on the credit product itself.
Banks and credit unions, along with the technology teams serving them, gravitate toward white-label and LaaS models for core credit operations. Retailers, marketplaces, and consumer brands, holding neither a license nor a credit stack, more often adopt embedded lending, BaaS, and co-branded programs to place financing inside a journey they already control.
| Model | Definition | Operational focus | Flexibility and maintenance |
|---|---|---|---|
| White-label lending | A third-party lending platform presented under the licensee's brand | The brand and borrower relationship stay with the business; the software comes from the vendor | Configured rather than coded, with scaling and upkeep handled by the vendor |
Embedded lending | Credit is integrated into a non-financial journey, most often an e-commerce checkout | Conversion depends on the host checkout design as much as on the credit logic | The front end adapts to the journey; processing stays on the vendor's side |
| LaaS | Ready-made lending technology reached through cloud APIs on subscription | Modules are billed as consumed on a recurring or volume tier | APIs open up the front end; the vendor owns the uptime and the database |
| BaaS | Accounts and regulated banking rails supplied by an institution that holds the license | Charter and ledger sit with the bank, and clearing access comes with them | The sponsor bank sets the rules for changes, so updates follow its approvals |
| Private label / Co-branded lending | A credit product issued under one company's brand, or under two jointly | The brand is out front; the lender of record may never become visible to the borrower | Underwriting, reporting, and portfolio risk remain with the partner bank |
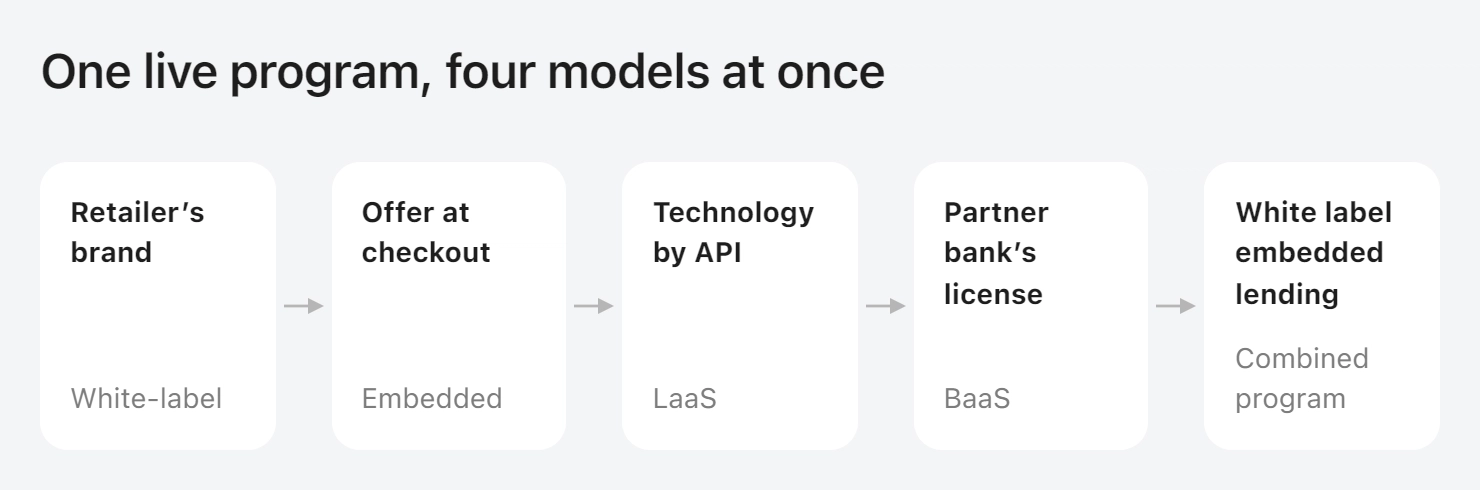
However, none of the five models excludes the others, and most live programs combine them. A retailer's brand on a checkout offer, technology rented by API, and a license borrowed from a partner bank together produce white label embedded lending.
What are the Key Benefits of White Label Lending?
Fintechs and banks comparing white label lending solutions look at six benefits in particular.
1. Reduced Development Costs
Developing a lending platform from scratch often means salaries for an engineering team, ongoing infrastructure spending, and constant work to keep compliance current. Even a minimal team costs several hundred thousand dollars a year in base pay, before benefits, hardware, or recruitment. With a white-label platform, development costs are shared across clients, allowing businesses to allocate more resources to customer acquisition instead.
2. Quicker Launch Times
An in-house build generally runs well beyond a year to reach production, whereas a standard white label solution setup takes from three months and heavily customized projects to six months or longer.
Much of the implementation timeline is nevertheless set on the lender's side by how many products are going live at once, the mandatory integrations, the legacy data to migrate, and, under a bank partnership, the length of the bank's own review.
3. Proven Software Stability
Early-stage lending systems, often prone to bugs and downtime, frustrate customers and erode trust. Most of them arise in partial payments, early payoff recalculations, and month-end reconciliation with the processor.
White-label platforms have been deployed across many lenders' portfolios, and that history of production use is part of what a lender buys with the software.
4. Regulatory and Compliance Support
Rules change faster than a small legal team can track them. A white label lending platform provides configurable KYC checks, fraud monitoring, audit trails, and role-based access controls, and it keeps the records an examiner can review.
The platform supplies controls and evidence and the records, and responsibility for meeting local requirements stays with the lender.
5. Scalable Operations and New Customer Segments
White-label platforms let businesses handle rising loan volumes and broader customer bases without redesigning their architecture each time, because added volume is handled by scaling infrastructure and adjusting configuration. A lender can plan for both steady growth and sudden surges on the same setup.
A configurable core also makes room for new product lines. White label consumer financing at a retail partner brings its own fee logic and decision rules, and a configurable core takes them on without a separate build.
6. Continuous Innovation and Core Workflow Focus
Keeping a lending system current is permanent work that competes with the lending itself. On a white-label platform, that work goes to the vendor. On hosted deployments, API patches, database upgrades, and feature releases are built once and shipped to every client, and the maintenance terms are set when they reach each installation.
Internal teams keep their hours for credit strategy, risk management, and customer relationships. For on-premises installations, the contract sets how and when updates are applied.
Licensing and the Lender of Record
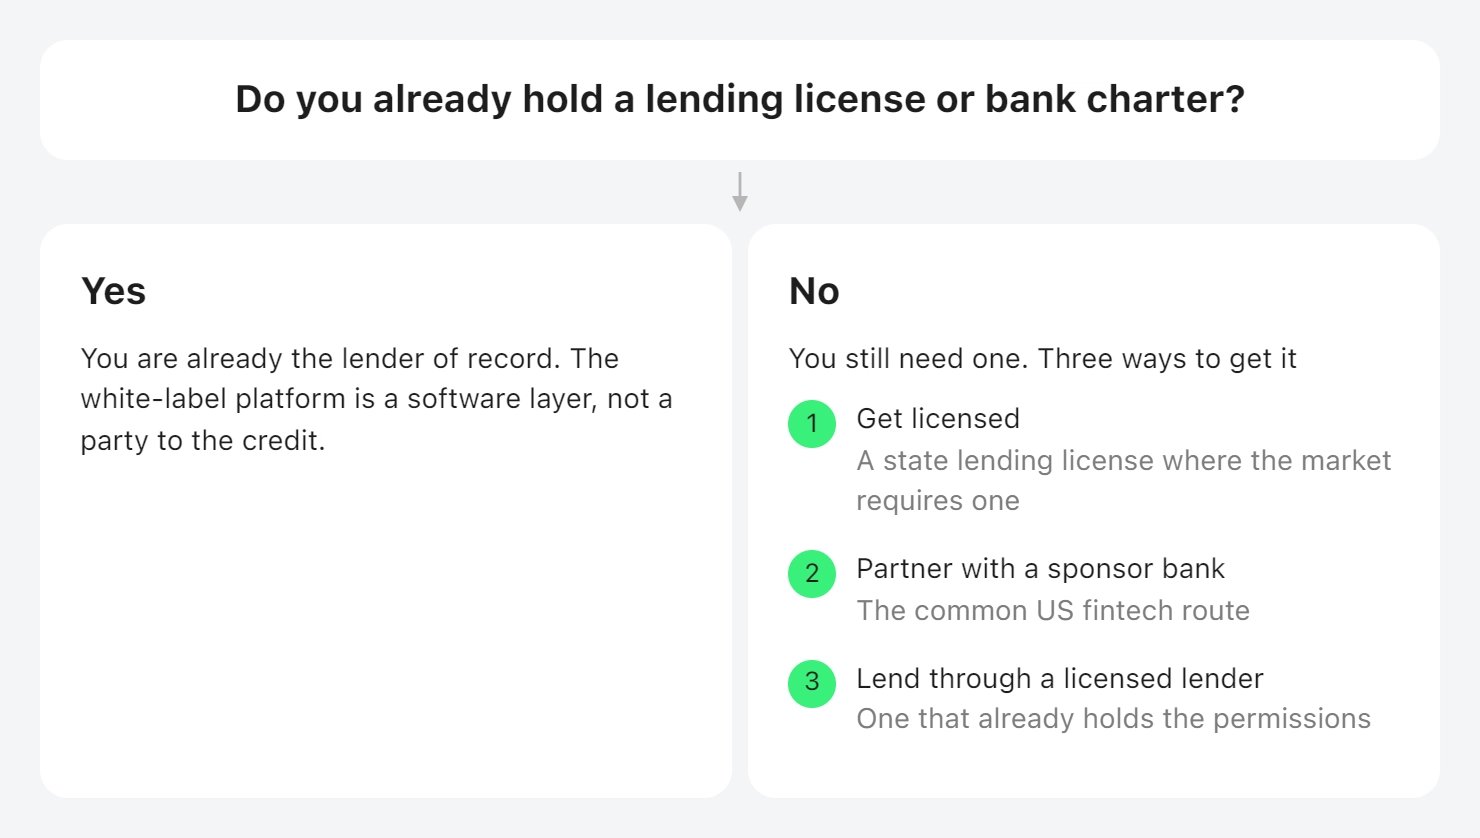
Licensing a white-label lending platform does not make a company the lender of record, the entity that legally originates the loan and answers to the regulator for it. Requirements shift with the loan type and with the market.
A bank lending on white-label software remains the lender of record itself, since the software is a layer rather than a party to the credit. Every other brand has to source that authority externally, and there are three routes to it:
- Becoming a licensed lender, with a state lending license where the market requires one.
- Working with a sponsor bank that originates the loans and supplies white label funding under a bank partnership.
- Lending through another licensed lender that already holds the necessary permissions.
The second route is common in US fintech. The bank takes on origination, funding, credit oversight, and the AML program, while the partner brand handles customer acquisition, product experience, and daily operations. That allocation is contractual and remains subject to supervisory expectations, and in the US courts and state regulators may apply a true lender test that looks past the paperwork to the originating lender. Elsewhere the structure changes again; for example, Indian rules require the loan to be made by an RBI-regulated bank or NBFC partner.
From the bank's side, the same arrangement is white label financing for banks, in which a chartered institution puts its balance sheet behind a partner's brand. A white label loan broker is different again, arranging loans for partner lenders and never becoming the lender of record.
White label table funding sits between the two. The loan closes in the partner’s name, but a third party advances the funds at the closing table and takes assignment of the loan at the same moment, so the originating brand never carries the asset. The arrangement is most common in US mortgage and correspondent lending, where it lets a brand originate under its own name without warehousing capital.
For the platform, table funding is a configuration task. The system has to record two parties on one closing, hold the funding condition until the investor confirms, and transfer servicing data to the funder at assignment. Under US rules, the party advancing the funds is treated as the originating lender for disclosure purposes, so the disclosures and the data flow follow the funder, not the brand on the document.
| Case | What typically applies |
|---|---|
| US consumer loans | State lending license or sponsor bank; Reg Z (TILA), ECOA, and FCRA rule on consumer disclosures, fair lending, and credit reports |
| US commercial and SME loans | Lighter licensing in many states, but several states, including California, New York, and Texas, require commercial financing disclosures |
| US mortgage | State-level licensing for nonbank mortgage companies and loan originators through NMLS. In table-funded transactions, the party receiving the initial loan assignment is considered the lender under RESPA Regulation X. |
| UK | FCA authorization for consumer credit; certain deferred payment credit products, commonly called BNPL, came under FCA regulation on 15 July 2026 |
| EU | National licensing: the revised Consumer Credit Directive, which covers certain BNPL products, applies from 20 November 2026, with requirements set by national transposition |
Aspects to Consider When Choosing a White Label Lending Platform for Your Business
1. Customization Capacity
The practical test is what a business can change without a developer. On a strong white label solution that covers the borrower portal and lender portal, loan products, decisioning parameters, and reporting formats.
2. APIs and Integrations
Typically, lending touches payment processors, credit bureaus, CRMs, and core banking systems, none of which belong to the lender. An API-first architecture reduces that exposure, and so do webhooks, a sandbox environment, mature API management, and connectors written for core banking integration.
Worth establishing separately is whether the vendor offers API-only access alongside the branded interface, since some teams want the lending flow headless, inside an application they already ship.
3. Total Cost of Ownership
Total cost of ownership covers the license, implementation, platform management, upgrades, and the cost of leaving, and it is the last of these where vendor lock-in becomes expensive: with white label services, exit terms agreed in year one determine what year four costs. The contract term, the exit clause, data ownership, and source code escrow belong in the review before signature.
4. Data Security and Compliance
IBM, in its 2026 Cost of a Data Breach Report, highlights that the average financial services breach cost $6.3 million, against a global average of $4.99 million.
A platform should therefore provide encryption at rest, secure hosting, penetration testing, and audit trails, and name the security standards it meets:
- ISO/IEC 27001 certification;
- SOC 2 report;
- PCI DSS if the platform handles card data;
- GDPR alignment for EU borrowers.
5. Vendor Support and Reliability
Support quality is tested at month-end, when a failed repayment run has to be resolved the same day. The service level agreement should be read for response times by severity, alongside the uptime guarantee and the disaster recovery plan, and a white label loan management system should be checked for single-tenant deployment or only multi-tenant deployment.
6. Integrated Feature Set
The last check is how much of the lifecycle one product already covers, from digital onboarding, automated underwriting, AI-powered credit scoring, loan management, payment scheduling, and analytics dashboards. A checklist of loan management system modules helps compare what each white label loan management software covers.
Most vendors price in one of three ways, generally on top of a one-time setup fee covering configuration and data migration. Published prices are rare in white label lending software, so comparison has to be assembled from quotes.
| Model | How it works | Typical fit |
|---|---|---|
| Flat license fee | A fixed annual or monthly fee | Volume that is steady or climbing fast |
| Per-transaction pricing | A fee on each application or funded loan | Pilots and launches where volume is uncertain |
| Revenue share | A percentage of program income | Partners who bring distribution or capital |
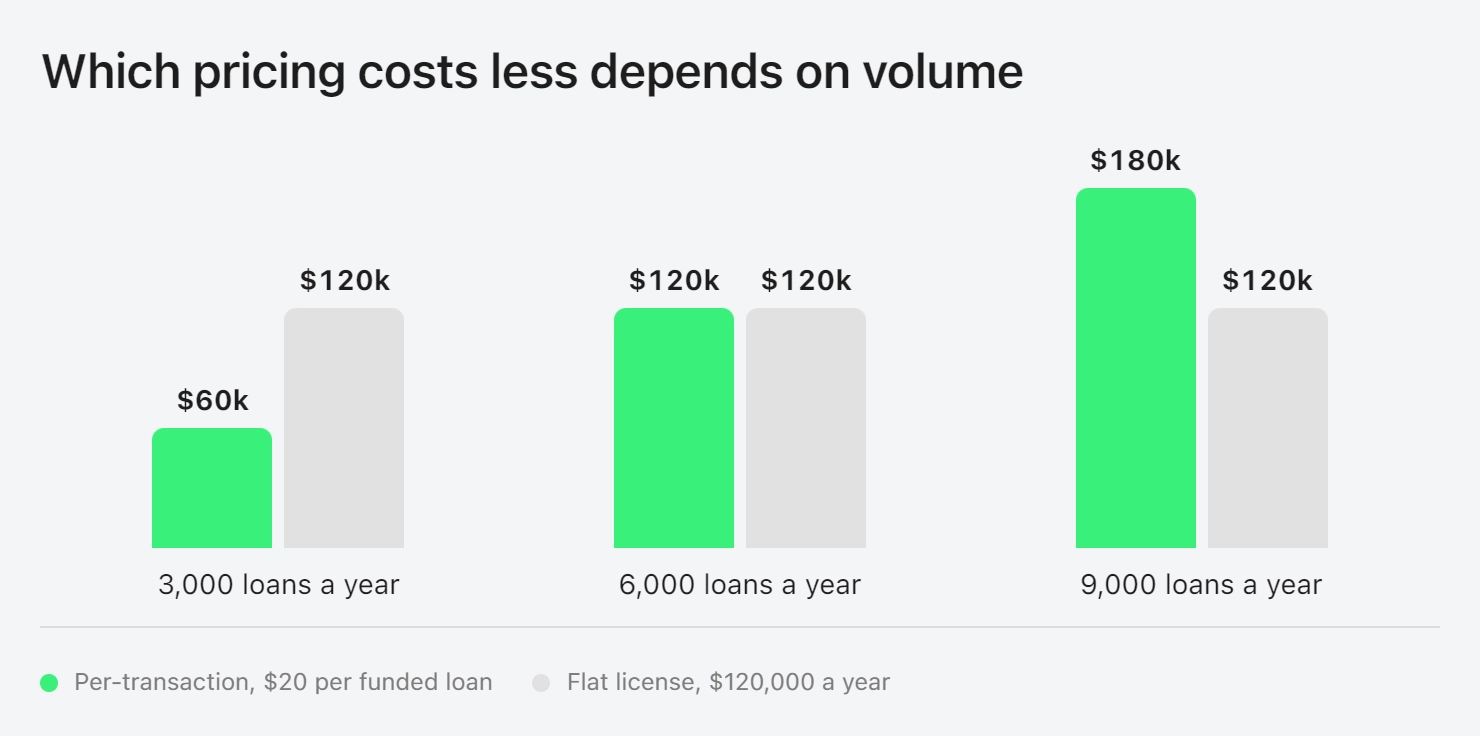
Early in a program, per-transaction pricing or a revenue share keeps the bill tied to what is actually originated, and beyond a certain volume, the flat license fee becomes cheaper. To find the crossover, divide the annual license fee by the per-loan fee. A hypothetical $120,000 license against $20 per funded loan places the break-even volume at 6,000 loans a year.
Revenue share behaves differently over a longer horizon, since the vendor's share grows with the portfolio. To compare the models fairly, price all three at launch, at year two, and at target volume.
White Label Finance Solutions by Vertical
The lending core changes little between credit types. The layer around it does, and that layer is usually where an implementation runs long.
| Vertical | Core platform requirements | Key operational focus |
|---|---|---|
| P2P and marketplace lending | Investor portals, wallets, auto-invest rules | Every repayment splits across investors, so the ledger carries both sides |
| Real estate and hard money lending | Collateral valuation, draw schedules, balloon terms | Asset-backed risk, with funds released against milestones |
| BNPL and POS lending | Checkout decisioning, merchant settlement, and decline waterfalls | Approvals at checkout speed. Declines move to the next lender in the waterfall |
| Credit builder and secured lending | Locked savings or deposit accounts, small-dollar amortization, bureau furnishing | Payment data has to reach the bureaus on schedule, and disputes come back through the same channel |
| Commercial, SME, and business funding | Covenants, invoice financing, merchant cash advance, equipment finance, pre-qualification on business data | Credit committee sign-off first, covenant tracking ever after |
| Mortgage lending | Escrow management, long-term amortization, disclosure tracking | Documents in volume and regulatory deadlines that do not move |
| Healthcare financing | Provider onboarding portals, patient payment plans | Bringing providers live and moving patients through intake |
Top 5 White-Label Lending Platforms Compared by Niche
White label lending software covers more ground than the category name suggests, and the five platforms below occupy different positions on it. Details come from each vendor's public materials.
1. HES LoanBox
Niche served: full-lifecycle white-label lending on one configurable core.
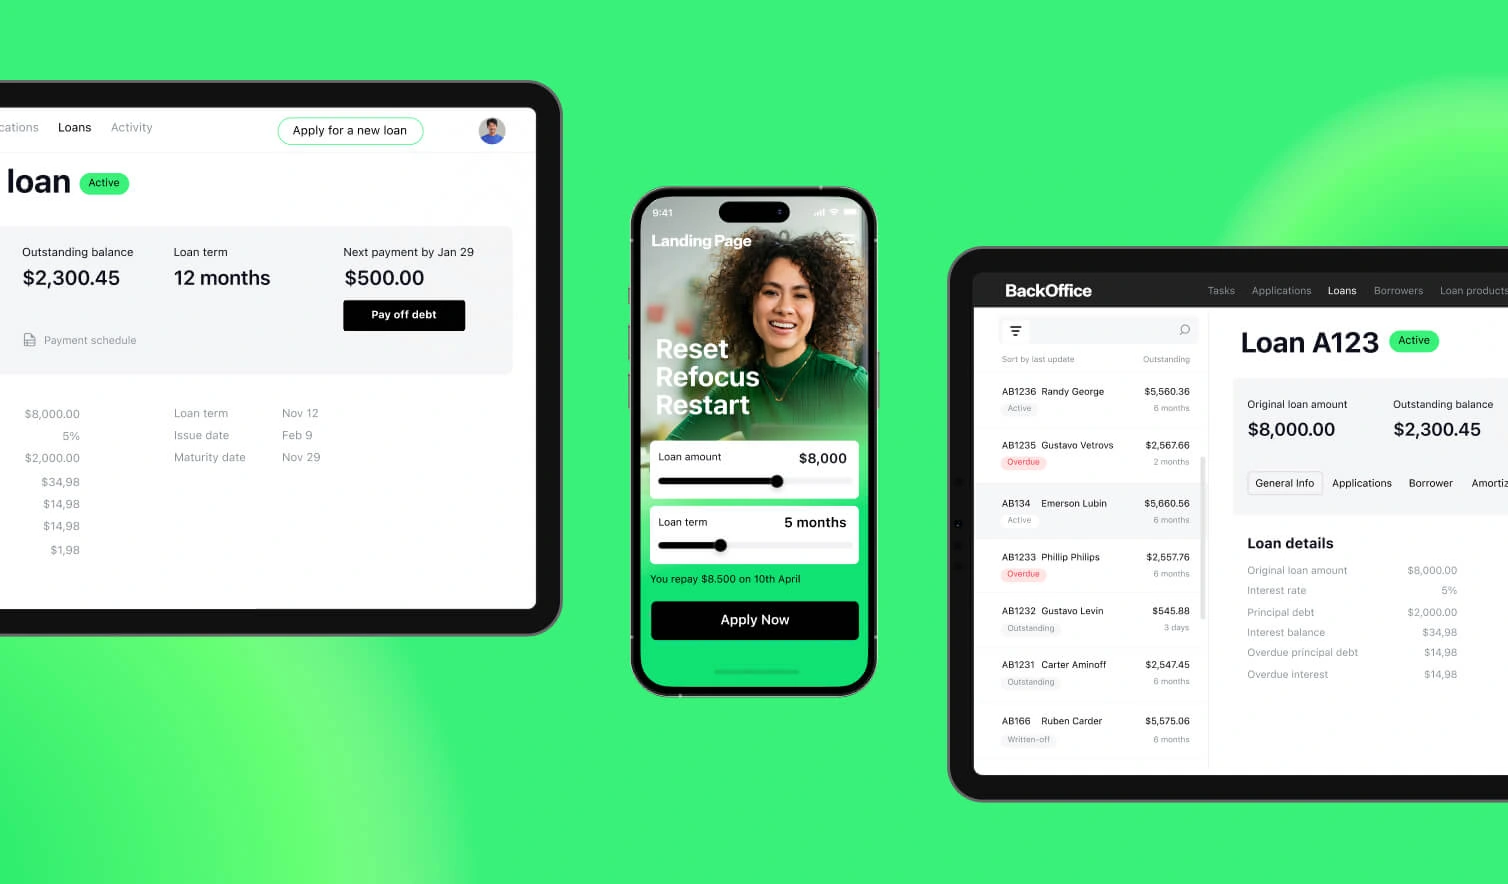
HES LoanBox manages several loan products side by side, covering digital onboarding, automated underwriting, servicing, debt collection tools, and credit decisioning. Borrowers work through a white-label portal the lender brands and controls.
The platform can be hosted on AWS, Google Cloud, or on-premises, and payment providers, credit bureaus, and other services connect through integrations. The vendor publishes ISO 27001 certification and SOC 2 alignment.
ML scoring is performed in GiniMachine, a separate HES product that connects as a scoring provider and trains on the lender's own loan history. LoanBox runs the lender's own operation, so it is not the lender of record and does not supply the lending license.
Commercial terms are quoted per project, without per-user licensing fees. Source code transfer is a separate option rather than part of the standard license for lenders that want full control of the platform code and no vendor lock-in.
2. FinMkt
Niche served: white-label point-of-sale lending for banks and credit unions.
FinMkt serves regulated lenders that finance purchases at the merchant, with a focus on areas such as home improvement, healthcare, and retail. A borrower can start an application in the store and move through prequalification, underwriting, electronic signature, and funding in one workflow, with the interface carrying the lender's own brand.
Real-time decisioning, soft-pull credit checks, fraud and KYC controls, and lender waterfall routing are part of the white-label platform, along with payment processing and on-demand reporting.
FinMkt does not underwrite on its own book. Applications route to the lenders in the waterfall, and the published scope runs from the merchant application through to funding. Costs are quoted per deployment rather than listed.
3. Jifiti
Niche served: white-label financing across a bank's own and embedded channels.
Jifiti covers bank and lender financing in both directions. Its white-label platform enables banks, credit unions, captive finance companies, and other regulated lenders to offer financing through their own websites and apps as well as through third-party merchant networks, from in-store POS to e-commerce checkout.
The platform carries a loan from application and decision-making through servicing and payment collection and on into delinquency work when a borrower stops paying. Borrower messaging runs from the same place. Approved funds reach the customer as a virtual card, a wallet credit, a POS settlement, or a direct transfer. Core banking, KYC, payments, and other third-party services connect through integrations.
Jifiti is not the lender of record, and mortgage lending falls outside the published scope. No price list is published; terms are quoted per program.
4. LenderKit
Niche served: white-label P2P lending and debt crowdfunding platforms.
LenderKit's software targets operators launching investment platforms, including real estate and SME lending models. Borrowers and investors get separate white-label portals, and the product covers onboarding, loan origination, payment processing, loan management, and repayments.
Platform operators can also configure investor features such as auto-investing and manage transactions through an administrative back office.
KYC/AML verification and credit scoring rely on third-party providers and integrations rather than being proprietary LenderKit services. Balance-sheet lending is not its primary use case. LenderKit lists Basic, Pro, and Enterprise packages alongside custom development, without published figures.
5. ChargeAfter
Niche served: white-label multi-lender checkout financing for retailers.
ChargeAfter's white-label platform gives retailers a single integration to offer financing from multiple lenders. Its core model is built around point-of-sale credit, with support for BNPL, installment, and revolving products, plus B2B and lease-to-own options through its lender network.
The platform matches an application to available lenders and can route it through a waterfall when the first lender does not approve it. Merchants manage lender relationships through a centralized interface across in-store, online, phone, and home sales.
ChargeAfter provides the technology and credit-distribution layer rather than the loan itself; financing comes from its third-party lender network. Pricing is agreed upon per merchant program and is not public.
Conclusion
White-label lending platforms lower upfront development costs and shorten time-to-market by supplying infrastructure a lender would otherwise build and then maintain indefinitely. Security features, compliance tooling, and configurable products arrive with it, which frees a team to concentrate on distribution rather than on core software upkeep.
Selecting the right platform comes down to customization limits, scaling capacity, security standards, and vendor support responsiveness. Integration depth matters as much, because every system the platform cannot reach turns into a manual export and a reconciliation task.
FAQ
What is white label lending?
White label lending is an arrangement where one company offers credit under its own brand using software built and operated by someone else. The borrower sees the licensee’s name, pricing, and terms; the vendor supplies the platform, hosting, and release cycle. The credit relationship and the underwriting policy stay with the business whose brand is on the product.
Who is the lender of record on a white label lending platform?
The software vendor is not the lender of record. A bank running white-label software remains the lender itself, since the software is a layer rather than a party to the credit. Every other brand sources that authority externally: by holding its own lending licence, by working with a sponsor bank, by lending through another licensed lender, or through table funding, where a third party advances the funds at closing and takes assignment of the loan.
How does white label financing differ from embedded lending?
White label financing describes whose brand the borrower sees: the credit is offered under the licensee’s name, on someone else’s technology. Embedded lending describes where the offer appears, which is inside a non-financial journey such as a checkout. The two overlap in practice. A retailer’s branded instalment offer at checkout is both white label and embedded, and the licence behind it may come from a sponsor bank under a separate arrangement.
What is a white label finance company, and does it lend its own money?
A white label finance company offers credit under its own brand using another provider’s technology, and in most cases another institution’s lending licence. Whether it lends its own money depends on the structure: a licensed lender funds from its own balance sheet, while a brand working with a sponsor bank distributes credit the bank originates and funds.
What should you compare when choosing white label lending software?
Six checks decide most selections: how much a business can reconfigure without a developer, whether the APIs reach the payment processors, bureaus, and core systems already in use, total cost of ownership including the exit terms, the named security standards the platform holds, support response times at month-end, and how much of the lifecycle one product already covers. Vendors differ less on features than on which parts of that list they leave to the licensee.
How much does a white label lending platform cost?
Published prices are rare, so comparison has to be assembled from quotes. Vendors generally price in one of three ways on top of a one-time setup fee.
A flat licence is a fixed annual or monthly sum that does not move with volume. Budgeting is simple and the cost per loan falls as origination grows, though a quiet quarter is billed the same as a busy one.
Per-transaction pricing charges on each application or on each funded loan, and that distinction matters more than the headline rate. The bill tracks activity, which keeps a pilot cheap while volume is uncertain and makes a mature programme the costliest of the three.
Revenue share takes a percentage of programme income — interest, fees, or both, depending on the contract. Nothing is owed before the programme earns, which suits partners contributing distribution or capital rather than cash upfront
How long does it take to launch a white label lending platform?
A standard white label setup runs from about three months, and heavily customised projects six months or longer. Much of the timeline depends on how many products go live at once, which integrations are mandatory, how much legacy data has to migrate, and, under a bank partnership, how long the bank’s own review takes.
Does a white label lending platform cover loan servicing, or only origination?
Full-cycle platforms cover both, though the split is worth checking vendor by vendor. Origination and credit scoring sit at the front end, and everything after disbursement sits behind it — repayment schedules, payment processing, document storage and retrieval, account updates, borrower communications, and collections. Reporting is running across the two. Borrowers are usually given a branded portal where they can check balances and payment history, see upcoming instalments, make a payment, and download statements without contacting the lender.
What is white label business funding?
White label business funding is working capital, merchant cash advance, or invoice finance offered under a distributor’s brand rather than the lender’s. The brand in front is usually an ISO, a broker, a vertical SaaS product, or a B2B marketplace; the capital comes from a partner lender. The distinguishing requirement is pre-qualification: an indicative offer returned from business data and a soft credit check before the applicant commits to a full application. Some platforms carry delinquency in the same system, others hand the file to a dedicated collections product, and that boundary is worth establishing before signature rather than after.