Growth in microfinance has moved to digital channels. One market estimate from Dataintelo puts the global online microfinance market at $128.4 billion by 2034, and the same shift seems to be reshaping the online microfinance platforms market. Lenders ask a narrower question, though. How do you serve more borrowers without hiring at the same rate? Microfinance lending platforms are what most institutions reach for.
Modern microfinance solutions cover a wide range of lending activities: borrower onboarding, automated credit decisioning, loan disbursement, repayment management, and portfolio monitoring.
This piece covers what microfinance lending platforms are and what they change for lenders and borrowers, then walks through the build.
What Is a Microfinance Lending Platform?
A microfinance lending platform is an end-to-end digital lending system for issuing and managing small loans to individuals and small businesses. The lender might be a bank, an NBFC, or a standalone microlender. Everything sits in one place: digital onboarding, borrower assessment, loan servicing, repayments, delinquency management, and portfolio management.
Where borrowers have thin credit files, or none at all, and limited access to a bank, microfinance solutions matter most. That is the financial inclusion argument. Capital reaches underserved borrowers, the self-employed, small traders, and family businesses that would otherwise fund a stock purchase or a slow month out of savings they do not have.
Collateral-free loans are common in this segment, opening borrowing to customers with nothing to pledge. Repayment history and cash flow assessment carry the risk instead, plus a group guarantee in some markets. The practical consequence: data quality matters more here than in secured lending, because there is nothing to repossess when an assessment turns out wrong.
How Does a Microfinance Lending Platform Work?
How the workflow runs depends on the lender’s business model and product mix and on whether field officers are involved at all. Most still run through a broadly similar sequence.
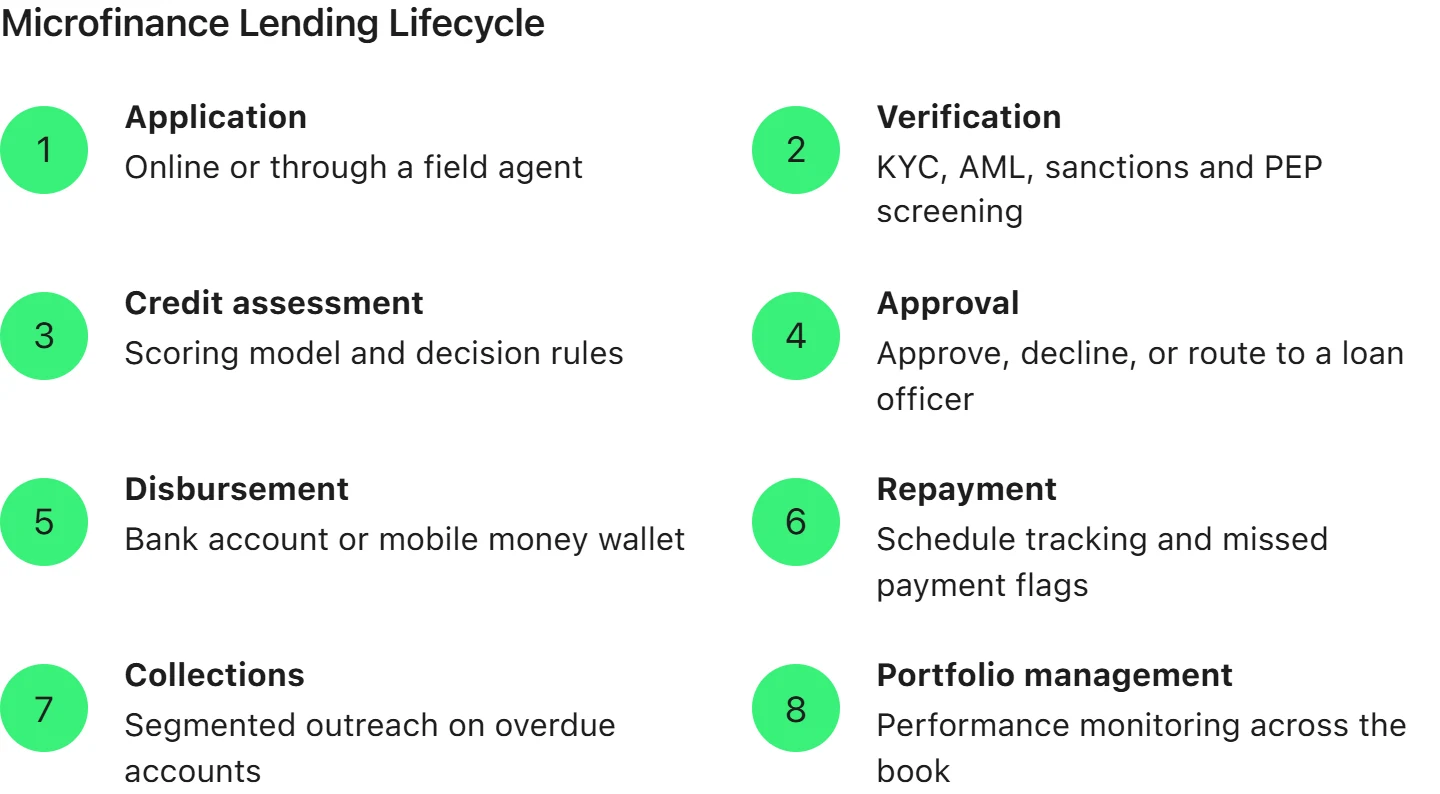
- Application. The borrower applies online or through a field agent and supplies the personal and business details the product asks for and whatever financial information the lender needs to see.
- Verification. The platform confirms identity and runs KYC and AML checks where required, including sanctions and politically exposed person (PEP) screening, then validates what was submitted against it.
- Credit assessment. The microfinance technology behind the platform weighs the borrower’s financial profile and repayment capacity against the lender’s credit scoring model and decision rules.
- Approval. The application is approved, declined, or sent to a loan officer for review, depending on how the rules resolve.
- Disbursement. Funds move to a bank account or a mobile money wallet, whichever channel the lender has connected to. Across much of Sub-Saharan Africa and South Asia, the wallet is the default, not the fallback.
- Repayment. Behind that, the platform builds and tracks the repayment schedule. It posts payments as they arrive, adjusting the balance each time, and flags anything missed.
- Collections. Accounts that stay overdue move to a separate track, where the platform segments them and schedules outreach, logging what came of each contact.
- Portfolio management. A microfinance lender reads the platform’s data to watch performance and steer the book before problems compound.
Key Drivers of Microfinance Lending
Several forces have pushed demand for microloans up at once.
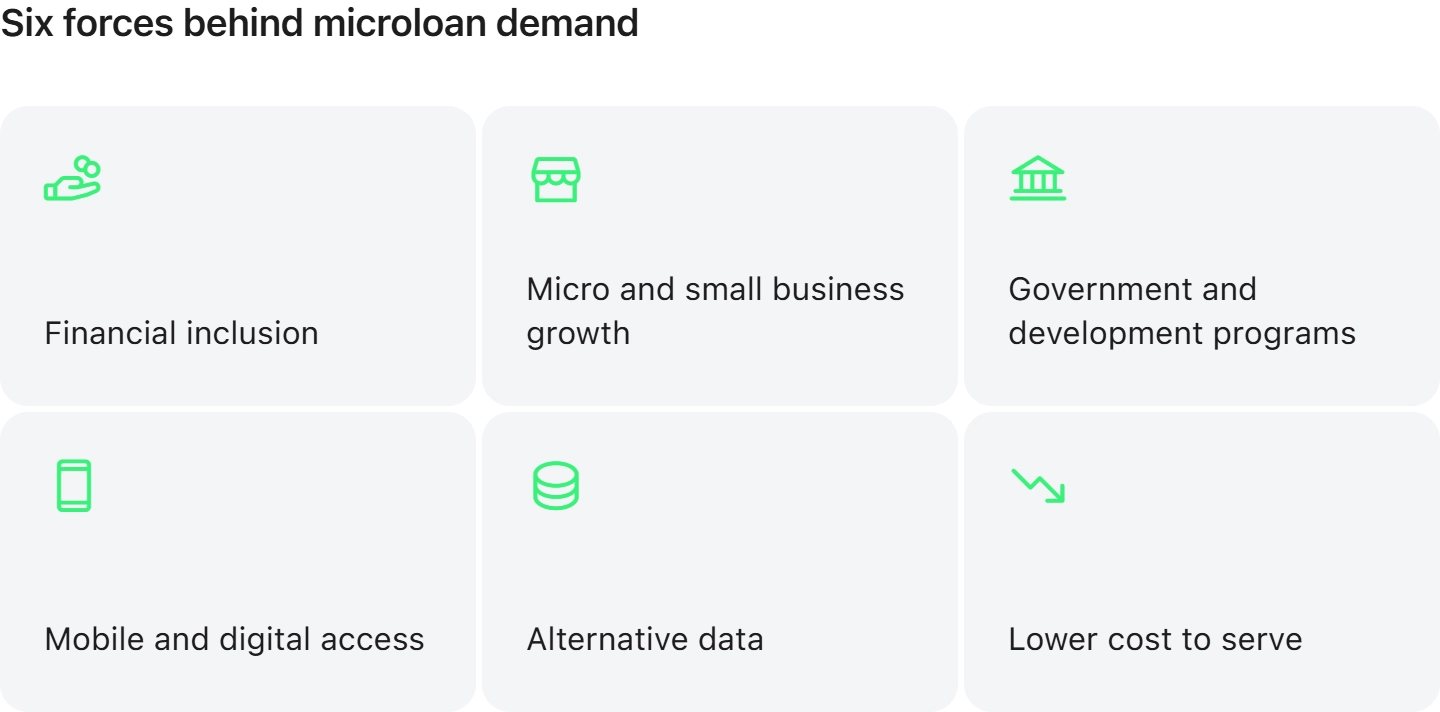
- Financial inclusion and underserved borrowers. Where conventional lending is hard to obtain, microfinance extends credit anyway. Demand concentrates in markets where a large share of the population sits outside conventional banking.
- Growth of micro and small businesses. Small businesses and self-employed borrowers often need fairly modest working capital finance, enough to cover operating expenses or buy a piece of equipment. Traditional lenders tend to be reluctant at that ticket size, and microfinance fills the gap.
- Government and development initiatives. Across emerging markets, governments in India, Brazil, and a number of African countries promote microfinance through policy and program funding designed to widen access to capital and support local economic activity.
- Wider mobile and digital financial access. Thanks to smartphones, mobile banking, and e-wallets, borrowers outside branch networks are now reachable. The same channels simplify loan disbursement and repayment, which usually cuts the cost and the operational risk of serving remote customers.
- Alternative data and improved credit assessment. Utility payments, mobile phone activity, transaction histories: non-traditional signals like these help lenders assess applicants with little or no formal credit history, where data protection rules and consent requirements allow. It widens the assessable population rather than replacing the credit file.
- Lower cost of serving borrowers. Microfinance technology can automate application processing, borrower verification, repayment tracking, and other routine work, which lowers what it costs to manage a single small loan. Unit economics are the binding constraint in microlending. A lower cost to serve is what makes small-ticket portfolios viable at scale.
The Role of AI in a Micro Lending Business
For microfinance lenders, AI processes borrower information faster and supports decisions across large application volumes. Models pick out patterns in financial behavior and flag suspicious activity. Where the traditional credit file is thin, they give an underwriter something to work with.
Governance travels with those gains, though. In the EU, creditworthiness assessment of natural persons sits in the AI Act’s Annex III high-risk category, though the Digital Omnibus on AI moved the compliance date for standalone Annex III systems from August 2026 to 2 December 2027, so lenders building now have a defined runway rather than an immediate obligation. In the US, a declined applicant is still owed the specific reasons behind the decision. A model that cannot explain its own output creates work rather than saving it.
Around the edges of lending, Generative AI takes on some of the routine work around lending. PwC points to its use in documentation such as model risk assessments and internal audit reports, and in routing exceptions to the right team. The payoff is narrow but real: less repetitive administrative work, more analyst time on cases that need judgment.
Benefits of Microfinance Loan Solutions
| Benefit | Operational impact |
|---|---|
| Faster loan processing | Automates routine steps in onboarding, verification, scoring, and approval |
| Lower operating costs | Cuts paperwork, rekeying, and repetitive administrative work |
| More informed credit decisions | Lets lenders tailor scoring logic and decision rules to each product |
| Wider borrower reach | Enables remote applications, digital payments, and access beyond branches |
| Improved repayment management | Automates schedules and reminders, and tracks delinquency for follow-up |
| Better portfolio visibility | Consolidates metrics into dashboards so managers can monitor delinquency risks and branch health |
| Easier business scaling | Supports configurable products, workflows, and lending rules |
A micro-finance solution makes lending operations easier to manage and gives lenders tighter control over the book.
The table above is the short version. Below, each benefit is unpacked in terms of what changes day-to-day for microfinance institutions.
1. Faster Loan Processing
Automate initial application review and borrower verification, along with the rest of the routine intake work, and an incoming application spends far less time sitting in the queue.
During digital onboarding, the platform can collect and validate applicant information, run predefined credit decisioning rules, and then route the application to the right scoring or underwriting workflow.
Where digital micro finance processes replace manual intake and data entry, application volume and underwriting headcount stop rising together.
2. Lower Operating Costs
Financial technology for microfinance cuts paperwork and repetitive data entry out of everyday operations, along with a good deal of manual calculation. Across loan origination, servicing, and collections, it automates enough that fewer files change hands between employees and systems.
What matters here is cost per active account, not cost per application. That is the number that decides whether a small-ticket book covers its own servicing.
3. More Informed Credit Decisions
Lending platforms such as HES LoanBox let lenders build their own credit assessment logic instead of accepting a fixed one and vary it by borrower profile and by product. Configurable credit scoring model rules define how each piece of borrower information gets weighed. That is what makes one platform workable for a salaried applicant and for a market trader with no pay stubs.
Where a lender wants statistical models rather than rules, GiniMachine is the separate HES product powered by AI technologies and covering that step. The engine builds scorecards on the lender’s own historical lending data and returns a probability of default alongside the factors behind it. It can also run next to an existing scorecard rather than replacing it.
4. Wider Access to Financial Services
Another benefit of microfinance software is reach: borrowers who live far from a branch or who have limited access to a bank at all.
Online applications and mobile channels cut down on repeat branch visits. Digital payments then make it easier to receive and repay a loan without going anywhere. A lender can serve rural or underserved areas without opening a branch in every new market.
In low-connectivity markets, field officers still matter, though. An offline-capable agent app usually sits alongside the borrower-facing channels rather than replacing them.
5. Improved Repayment Management
A lending platform automates much of the tracking and collection work. It generates the repayment schedule, updates balances as payments land, sends reminders, and flags overdue installments for follow-up.
Once accounts go past due, the job changes from tracking to building a recovery. HES CollectionAgent, for instance, scores delinquent accounts on repayment probability, separating borrowers who cannot pay from those who will not, and builds the collections workflow queue on expected recovery rather than on days past due and balance alone.
Actions then run within the limits the lender sets. The lender writes the message templates and sets the limits on tone and contact. Within those, the system picks the channel, timing, and how often to reach out, and every decision carries a logged reason.
Promise-to-pay is followed through to the actual payment, so an account that breaks its promise moves to a different track without waiting for a person to notice. Model inputs can extend to alternative data such as digital footprints, social signals, and behavioral indicators, where company policy and local data protection rules permit.
6. Better Portfolio Visibility
A microlending platform gives managers current information on loan performance, repayments, delinquency, and other portfolio indicators, without anyone stitching together exports from separate systems.
From there, integrated reporting and dashboards turn the raw data into views managers can act on: portfolio at risk by branch and product, collection rate, write-off trend. In microfinance, the figure that usually governs the conversation is PAR 30. The value of one system is that it produces the same PAR 30 for the branch manager, the risk team, and the funder, which sounds trivial until you have sat in a meeting where it did not.
7. Greater Business Scalability
A growing microfinance institution needs to serve more borrowers, launch new products, open branches, or move into new regions.
A flexible lending platform absorbs that growth through configurable products, workflows, lending rules, and integrations, so operations adapt without a rebuild of core functionality every time the business model shifts.
The thing to test during selection is not whether the platform can hold more accounts. It is how much of a new product launches through configuration and how much needs development work.
How to Develop a Microfinance Lending Platform
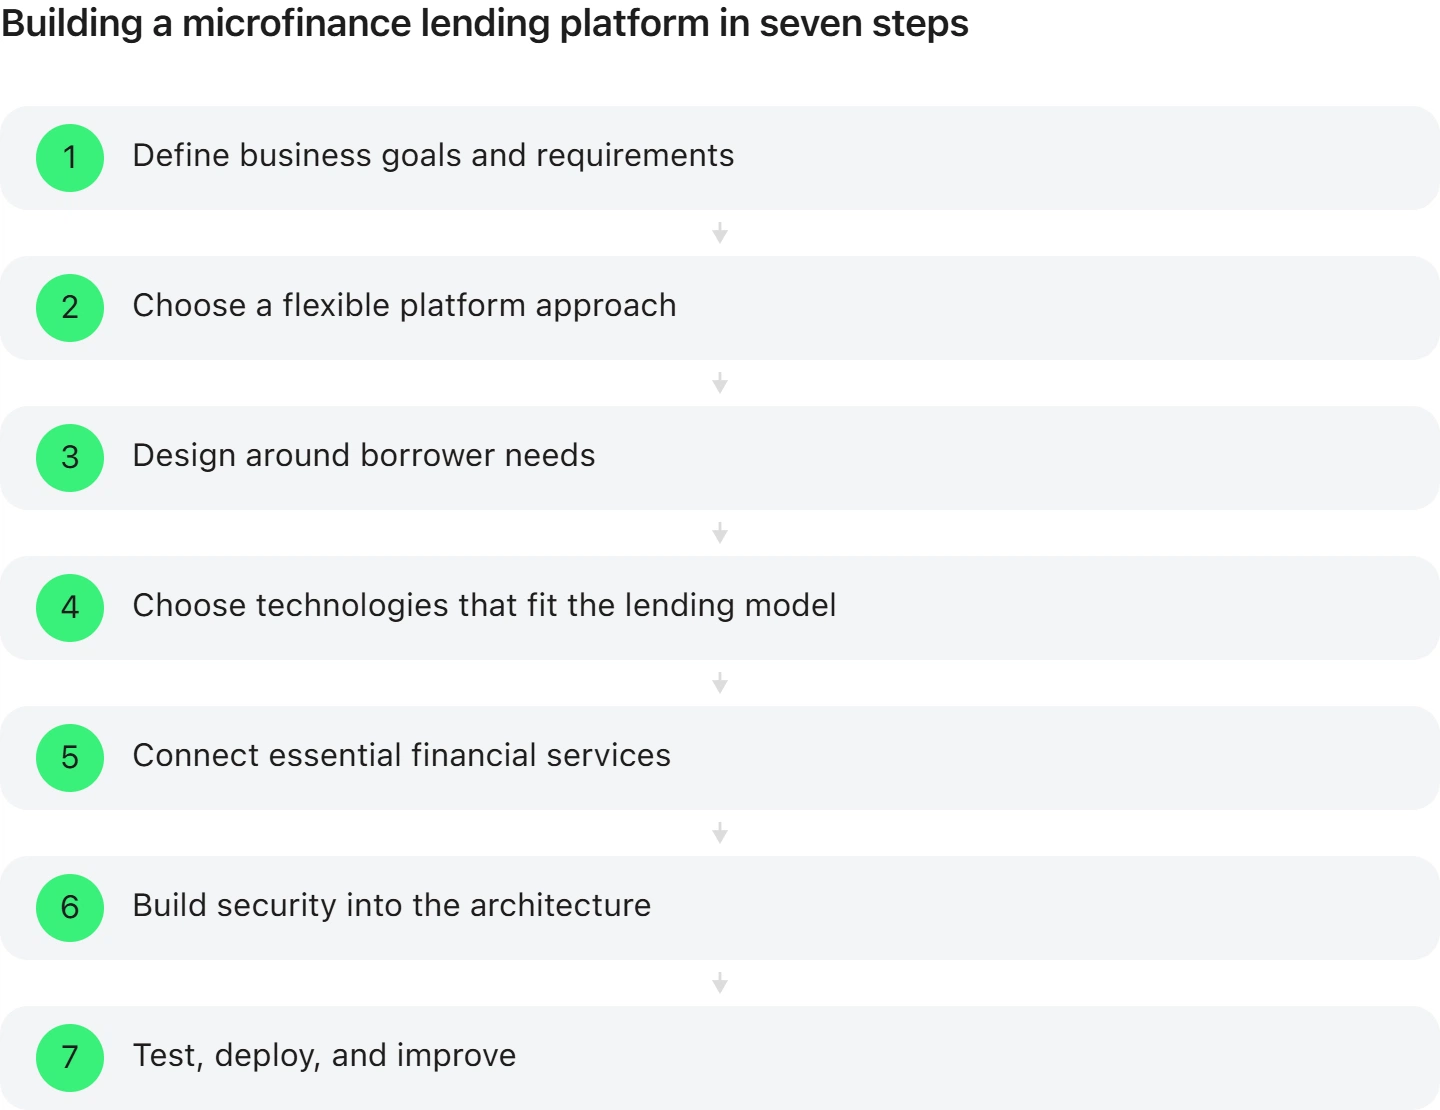
Step 1: Define Your Business Goals and Requirements
Given that you have a clear idea of why your microfinance institution requires investment in technology, it’s time to work on the detailed plan. For example, if your main goal is to cut operational costs, consider planning the service price including all possible adjacencies, and then cost out a realistic investment in the microfinance lending platform.
Exploring new business models can help identify new ways to serve borrowers and grow the business. For example, mobile banking technology, data analytics for credit scoring, automated decision-making, and digital loan underwriting can create new opportunities for microfinance institutions. AI-based solutions can also support a long-term growth strategy. The 2026 Global AI in Financial Services Report by the Cambridge Centre for Alternative Finance found that 81% of surveyed financial services firms are already adopting AI at some level.
Step 2: Choose a Flexible Lending Platform Approach
Surprisingly, some of the largest legacy costs in banking and financial services are IT systems (not brick-and-mortar offices). Closing a branch is considerably easier than financial data migration to the new software in terms of time and costs.
From our experience, most MFIs have to deal with platforms that are developed separately and hardly speak to each other. The most widespread problem is endless workarounds and quick-fix solutions that add manual work and impede automation. Digitizing the existing and future data via customized reports, dashboards, and CRMs is the capability MFIs usually seek in lending platforms.
However, when automating, it is vital to pick the proper balance between technology and the human touch. Research your market: some microfinance customers may not be ready for an end-to-end digital financial product or service. A 2025 CGAP report on financing for nano, micro, and small enterprises highlights the importance of hybrid business models that combine digital finance with human touchpoints, particularly for underserved borrowers.
Step 3: Design the Platform Around Borrower Needs
Understanding the customer needs and, what’s more important, caring about them, are vital steps in launching a successful microfinance lending business. The 2025 Microfinance Index highlights the need for financial service providers to move beyond one-size-fits-all approaches toward targeted service delivery, guided by client needs and feedback.
Regulators are also interested in enabling financial inclusion and mitigating risks. A recent report from the Alliance for Financial Inclusion contains recommendations and ideas that can potentially help reach synergy between digital finance service providers, fintechs, and MFIs in inclusive lending.
This is the key competitive advantage of microfinance lending as a whole: their being close to the needs of borrowers. In the digital channel, it means analyzing alternative data (like mobile phone top-ups or social media profiles) in order to deliver personalized offers and better understand risks and opportunities.
Step 4: Choose Technologies That Support Your Lending Model
Your technology stack should reflect how the business actually runs: how borrowers apply, how field officers work with customers, how money moves. Those choices turn on the operational model, target market, expected transaction volumes, and regional connectivity.
If you rely on field operations, you may need a dedicated field agent app with offline mode, so officers can register borrowers and update records wherever the connection drops out. Digital-first lenders tend to prioritize something else: mobile applications, automated decision engines, and direct payment integrations.
At the integration level, the platform should connect securely with banks, payment providers, credit bureaus, identity verification platforms, and mobile money services through API integrations. Bureau coverage is thin in many micro finance solution markets, so the integration list often leans harder on mobile money and telco data than on a credit file. These connections cut manual data entry and reconciliation while helping automate loan disbursement and repayment collection. With a modular software architecture, you can swap a component or add an integration later without disturbing the rest.
For larger or fast-growing institutions, a cloud-native architecture built around microservices adds flexibility. Key components are separated into independent services that can be updated and scaled on their own: lending, payment processing, notifications, customer management.
A micro lending business can then introduce products, absorb higher transaction volumes, and move into new markets with fewer limits from the underlying technology. The trade-off is operational. More services usually mean more deployment surface and more monitoring, plus distributed transactions to reason about. The architecture earns its keep when transaction volume or team size makes a single deployable unit the bottleneck, and not before.
Step 5: Connect the Platform With Essential Financial Services
Financial services providers, both banks and non-banking financial institutions, can search for partnership opportunities or integrate with each other, making it mutually beneficial.
In general, partnerships between financial institutions and fintech companies may play a crucial role in promoting fair lending.
By focusing on collaboration instead of competition and leveraging the digital infrastructure, MFIs can boost their customer outreach, including new channels, and simplify their customer acquisition. It’s a remarkable trend of MFI partnerships in developing countries, while it helps to provide more choice for consumers, drive institutional-level innovation, and help incumbent financial institutions use their resources to stay at the competitive edge.
Step 6: Build Security Into the Platform Architecture
Because a micro finance lending platform handles sensitive identity, financial, and transaction records, security belongs in the architecture from the start. The engineering team needs clear strategies for how data is encrypted, stored, transmitted, and accessed across its lifecycle.
Inside the system, access management is the first control that matters. Role-based access restricts sensitive operations to authorized employees. An audit trail records what changed and who changed it: borrower profiles, loan terms, approval decisions, and repayment entries. Together, they improve accountability and support compliance reviews.
Segregation of duties belongs here, too. In field-based lending, one officer originating a loan, collecting the cash, and adjusting the balance is the classic fraud pattern, and maker-checker approval on disbursement and write-off is the standard answer to it.
External connections need protecting as well, particularly those involving payment processing, banking systems, and identity verification. That means secure authentication, protected API endpoints, input validation, and monitoring that catches unusual activity.
Market and data type decide what else applies. GDPR is a legal obligation wherever EU personal data is involved. ISO 27001 and SOC 2 are different instruments: a certifiable management standard and an attestation report a service organization obtains. Neither substitutes for the other, and neither of them substitutes for local regulatory compliance obligations in the lending market itself.
Under the same heading sit reliability and business continuity. Automated backups, infrastructure redundancy, uptime monitoring, and tested recovery procedures reduce disruption when something fails. Backups only count once a restore has been rehearsed against a stated RTO and RPO. Building these safeguards in early is considerably easier than retrofitting them once the system holds real volumes of borrower and transaction data.
Step 7: Test, Deploy, and Improve the Platform
Before launch, put the platform through real lending scenarios. The full cycle needs validating: interest calculations, approval rules, repayment schedule generation, loan disbursements, payment processing, user permissions. Interest and fee calculation deserves the most attention, since flat-rate and declining-balance products produce different schedules from the same nominal rate, and a rounding rule applied at the wrong step shows up across the whole book. Simulate the operational failures too: failed payment callbacks, duplicate transactions, unstable connections, sudden spikes in application volume.
Rolling out in phases usually reduces operational risk, especially when you are replacing a legacy system or entering a new market. Release to a limited group of users, a single branch, or one loan product, then collect feedback and watch performance before widening the deployment.
After go-live, the work shifts to monitoring and iteration. Operational metrics come first: payment posting failures, disbursement latency, error rates by integration. Credit metrics come second, and they are the ones teams forget, because a scoring model built on pre-launch data starts drifting as soon as the borrower mix changes. A schedule for revalidating that model matters more than the feature release cadence.
Conclusion
A microfinance lending platform can help lenders lower operating costs, make more informed credit decisions, scale their lending operations, and reach more borrowers.
To develop one, start by defining your business goals and borrower needs, then choose a flexible platform, the right technology and integrations, and appropriate security measures. Test the platform with real lending scenarios before deployment and continue improving it based on performance and customer feedback.